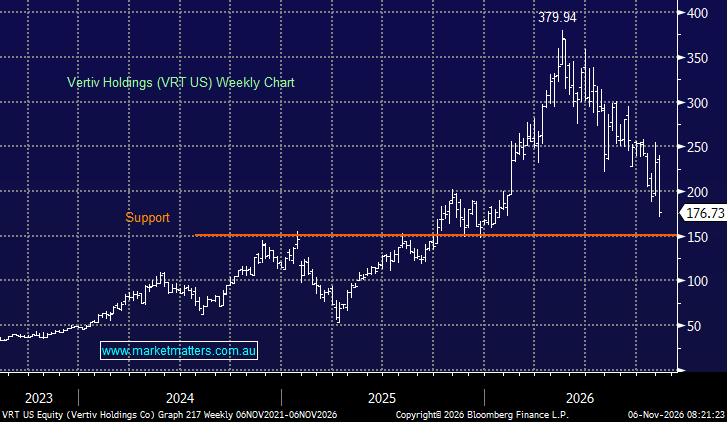
Vertiv supplies the critical power-management and cooling equipment that enables data centres to operate reliably, making it a key picks-and-shovels beneficiary of the AI investment boom. However, it has been among the hardest-hit data-centre-exposed stocks, reflecting its significant reliance on data-centre capital expenditure. The obvious concern is that any slowdown in US data-centre construction could directly affect new orders and future revenue growth.
The stocks already tumbled more than 20% this week despite earnings nearly doubling over the past year; its forward P/E has collapsed from ~36x to well below 20x, as the market reprices the risk that the AI data centre buildout faces a structural slowdown under a Democratic Congress. i.e. strong earnings delivery has been entirely offset by de-rating.
- We can see VRT finding support in the next ~5% as calm returns to the sector.