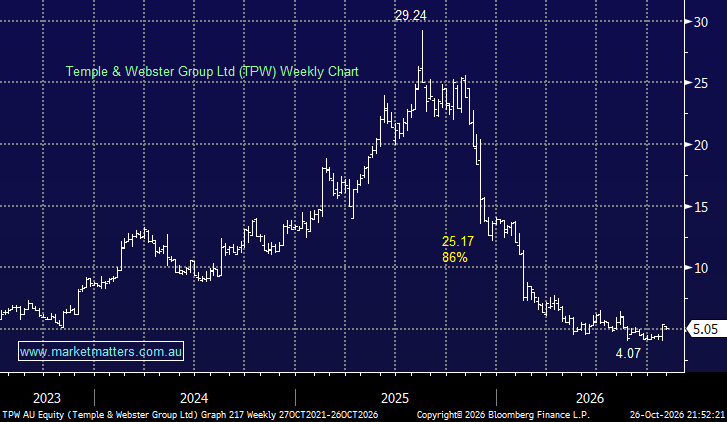
Temple & Webster (TPW) has endured an awful year driven by three compounding factors: repeated earnings disappointments that undermined its growth narrative, margin pressure from aggressive competitive discounting, and a sharp de-rating of a valuation that had priced in better execution. However, TPW reaffirmed its FY27 EBITDA guidance of $33–40m, implying 50–80% growth on FY26, despite a challenging consumer environment. Year-to-date revenue is down 8% year-on-year, broadly in line with expectations, while the revenue trajectory has improved from a 13% decline to 4%, i.e., less bad. More importantly, contribution margin dollars are up 16% year-on-year, well ahead of consensus expectations for around 9–10% growth in 1H27.
- This translates to contribution margins having recovered from around 10% at its FY26 trading update to an estimated 21% run-rate in the most recent period, demonstrating strong execution on profitability.
The pivotal question is whether TPW can sustain this improvement as it moves through the remainder of 1H27, when comparable sales conditions become more challenging again. While the softer revenue outlook creates some risk to consensus forecasts, maintaining the year-to-date contribution margin improvement could deliver upside. Management expects revenue growth to resume from late February as promotional comparisons ease, with sustainable double-digit growth targeted from FY28. Reaffirmed guidance is encouraging, but delivery will depend on balancing margin discipline with a return to stronger sales growth.
TPW has shrunk to a business worth less than $600mn, yet its valuation still looks demanding given FY27 profit is only expected to be around $16mn, though when looking at TPW, we think margins remain the key to this business.
- We can see the next 20% for TPW being on the upside, and believe the turnaround is showing some more positive signs. This is certainly a stock worth keeping on the radar.
MM is cautiously bullish towards TPW as a trading buy
Add To Hit List