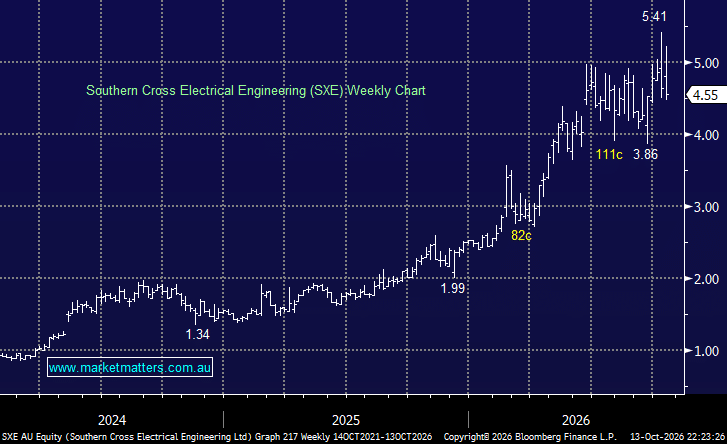
SXE has been one of the standout small-cap industrial performers over recent years, driven by strong exposure to data centres, infrastructure and electrification. Monday’s acquisition of Entire Operations adds another leg to the story, expanding SXE further into fire protection and, importantly, mechanical/HVAC services.
SXE is acquiring Entire for up to $112.1m, comprising $70m upfront and up to $42.1m of earn-outs linked to earnings targets through FY29. Entire generated $191m of revenue and $17.5m of EBIT in FY26, with around 35% of revenue coming from service and maintenance and roughly 25% from data centres.
We think there are a few interesting aspects to the deal:
- It adds meaningful scale in Victoria, while broadening SXE’s national footprint.
- It takes SXE into mechanical/HVAC, complementing its existing electrical, communications and fire capabilities.
- It increases recurring service and maintenance revenue, helping smooth what has traditionally been a project-driven earnings profile.
- There is obvious cross-selling potential across data centres, where clients increasingly want integrated electrical, fire and mechanical solutions.
Importantly, SXE is funding the acquisition from existing cash reserves rather than issuing more equity. Management expects the transaction to be at least 18% EPS accretive on an FY27 pro-forma basis, while FY27 EBITDA guidance has been lifted from at least $100m to at least $110m, including around $10m from Entire following an assumed November completion.
The earn-out structure also looks sensible, with a meaningful portion of the purchase price only paid if Entire continues to deliver against earnings targets. That reduces some of the risk compared with paying the full consideration upfront.
The deal prompted further broker upgrades, although the stock fell on the news. Macquarie reinforced it’s buy rating and upgraded its price target to $6 (from $5.59), factoring in the earnings accretion from the acquisition, making them the most bullish broker on the street. At the current price of $4.55, that still implies reasonable upside, although expectations have clearly moved higher after the stock’s very strong run over the past 12 months especially.
That is the key issue for us. SXE has gone from being obviously cheap to a business where investors are increasingly paying for continued execution. Consensus has FY27 EPS at around 21.5c, putting the stock on roughly 21x FY27 earnings, before falling toward 17x FY28 as earnings grow. As the proportion of reoccurring earnings expands, it should justify a higher multiple over time, however the stock does look frothy at current levels – we wouldn’t be surprised to see it cool off in the short term as stocks linked to data centre construction take a short term hit to sentiment following the failed Firmus IPO.
Overall, we think the Entire acquisition broadens SXE’s capabilities, increases recurring revenue and strengthens its position in the data-centre and infrastructure investment cycle, while the acquisition is immediately earnings accretive without requiring an equity raise. However, after the huge run in the share price, valuation is becoming more demanding. The acquisition needs to deliver, but at this stage it looks like another sensible piece of the SXE growth strategy rather than a reason to become too cautious on the stock.
MM is neutral SXE ~$4.50
Add To Hit List
chart

Southern Cross Electrical Engineering (SXE)
chart
Southern Cross Electrical Engineering (SXE)