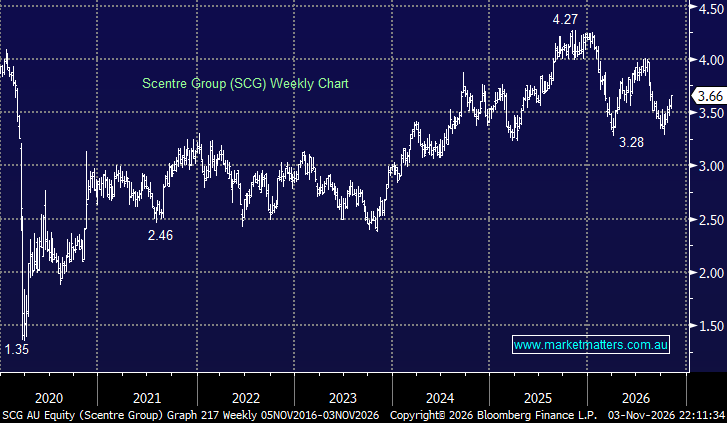
We are bullish on the ASX REIT sector, largely because we believe the RBA has reached the peak in interest rates. We already have exposure through Mirvac (MGR) and Charter Hall Long WALE REIT (CLW) in the Income Portfolio, so we’re unlikely to add a 3rd holding, but we do see SCG continuing to improve after a difficult period.
SCG owns 42 Westfield destinations across Australia and New Zealand and continues to deliver very solid operating numbers despite a difficult consumer backdrop. At the half, Funds From Operations (FFO), which is essentially the equivalent of EPS for a REIT (excluding the impact of property revaluations), rose 4.4% to $612m, distributions increased 4.9%, occupancy remained at an exceptional 99.8%, specialty sales grew 5.4%, and average releasing spreads were +3.7%. Management subsequently upgraded FY26 FFO and distribution guidance, with full-year distributions now expected to rise 4.25% to 18.47c per security.
The balance sheet is also better insulated from higher rates than the headline cash rate might suggest. At June, 95% of debt was hedged at an average base rate of 3.26%, while liquidity of $3.5bn covered all maturities until the second half of 2028. This is an important piece of the puzzle, because the bear case on REITs is that higher bond yields reduce the relative appeal of distributions, increase refinancing costs and pressure asset values. If the RBA is now at the top of the cycle, those headwinds should progressively ease.
The key question is whether SCG’s roughly 5% yield is enough with cash at 4.85%. On income alone, perhaps not. But investors are also getting modest distribution growth, high-quality assets, improving rental economics and potential capital upside if bond yields eventually move lower.
Given our holdings in MGR and CLW in the Income Portfolio, we are not short of REIT exposure, but SCG is also looking increasingly interesting. Its operating performance remains strong, the debt book provides good near-term protection from higher rates, and its dominant Westfield assets should continue to compound earnings through the cycle.
- If our view is right on rates, the broader REIT sector should start to see some love return, with yesterday’s share price gains the potential start of a meaningful recovery. SCG is one of the higher-quality ways to play it.
MM is bullish SCG ~$3.60
Add To Hit List