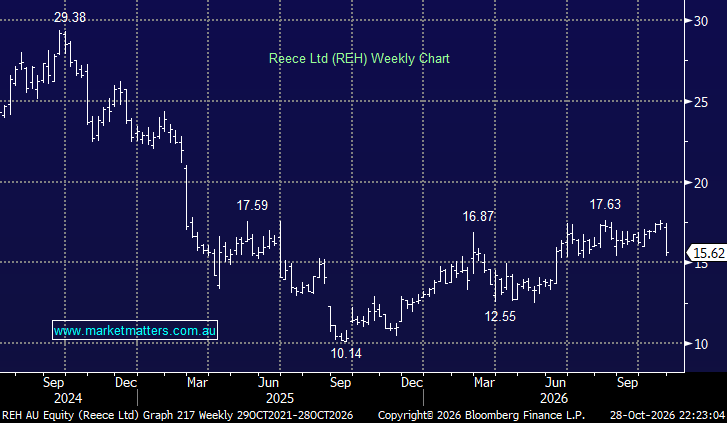
After testing 18-month highs earlier this week REH was smacked almost 9% yesterday making it the worst performer on the main board. The stock, like so many have of late, suffered at the hands of broker downgrades: Citi cut it to a Sell, from Neutral, with a $16.10 target, while Jeffries tweaked its price target down almost 2% to $16.60 – both PT’s above yesterday’s close.
- The downgrades were focused around the weaker macroeconomic backdrop and persistent affordability issues from higher interest rates and elevated inflation – same story, different day.
The sell-off gathered momentum following the hot CPI, with Reece particularly exposed to interest-rate expectations given its reliance on residential construction, renovation and plumbing demand in Australia, alongside its sizeable US business. Higher borrowing costs risk further pressuring housing activity and discretionary spending, while a higher discount rate reduces the appeal of stocks valued on earnings growth moving forward. The fall was also amplified by REH’s recent share-price rally, and it will be interesting to see if we see follow-through selling this morning.
REH is trading ~10% below its long-term average valuation, basically what it dropped yesterday, suggesting support on a value basis isn’t going to arrive soon. Our REH thesis is largely predicated on their strategy of continuing to invest in the US through the downturn, which we believe will yield results in the medium term, but clearly there are some short-term headwinds now at play.
- We are closely watching our position in REH, and will not hesitate to cut the position if it fails to bounce following yesterdays 1-2 of broker downgrades.
MM is long and cautiously bullish towards REH
Add To Hit List