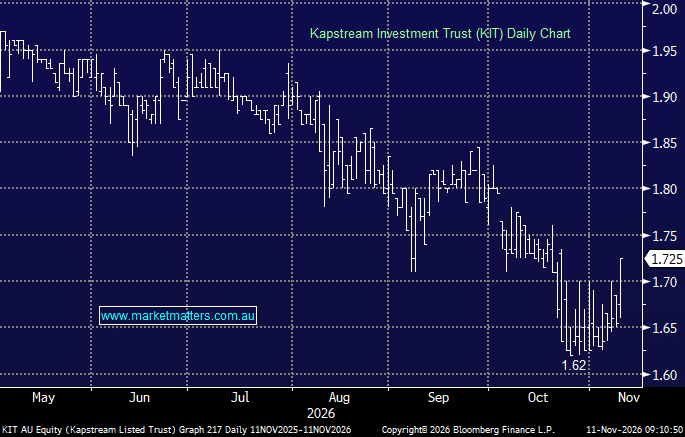
We are buying KIT for a combination of its yield, and potential for it to narrow its discount to NTA, providing upside from capital growth. KIT trades at a ~14.3% discount to its net tangible assets (NTA), offering a running distribution yield of ~9.4%. At the current price, we’re effectively purchasing ~$2.00 of underlying assets for $1.70. KIT’s recently announced on-market buy back of up to 5% of units on issue will also provide some support. While we remain cautious on parts of the private credit market, we are comfortable with KIT given their risk is adequately diversified – the majority of KIT’s lending is in warehouse loans rather than higher risk individual property developments.
NB: Low liquidity – we are using a limit price of $1.73.
MM is buying KIT in the Active Income Portfolio, allocating 4% around $1.70
Add To Hit List

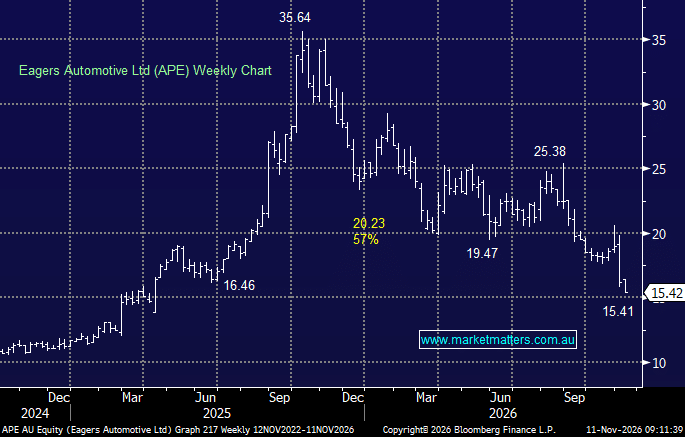
We are trimming our position in Eagers despite only purchasing the stock recently – the company issued a disappointing trading update with the stock subsequently selling off – our first price-action sell signal has been triggered, prompting us to reduce its target portfolio weight to 2% in line with our portfolio management framework. While we still see value in the stock around ~$15.50, we are taking a cautious approach – the reduced weight reflects the downside risks around weaker consumer spending and the market’s continued sensitivity to earnings disappointments/downgrades.
MM is trimming APE in the Active Income Portfolio, reducing to a 2% target weighting~$15.40
Add To Hit List