Is it just me, or is McDonalds no longer the cheap option? That question sits at the heart of one of the key issues facing the business. Higher menu prices have weakened McDonald’s traditional value proposition, particularly for lower-income US consumers, contributing to softer traffic and sluggish same-store sales. However, the sharp sell-off through August and September was driven by more than just consumer pressure.
On their 23 September Investor Day, management guided to slightly negative US comparable sales for Q3 and outlined a significant step-up in investment, including around US$3bn of annual capex from 2027–30 as part of its NEXT restaurant modernisation and technology program. The combination of weaker near-term sales and heavier spending triggered a material de-rating lower in the stock (although it has partially recovered since).
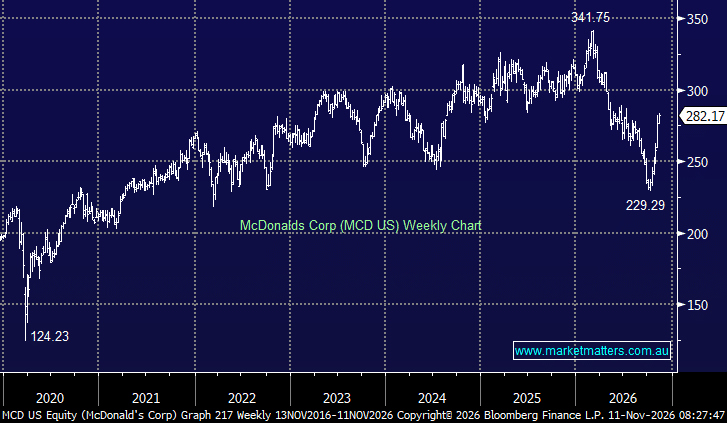
That came on top of already softer 2Q US comps, while concerns around franchisee economics and the cost of store upgrades added further pressure. The stock subsequently fell from around US$340 to the low-US$230s. The important point for us is that none of this changes what has made McDonald’s such a strong long-term winner. Everytime, without fail, short term weakness is overcome by a steady climb higher in both earnings and therefore the share price. This makes it an attractive, lower beta, defensive style position worth considering, potentially as a replacement for our existing (defensive) positon in additives business, Ashland (ASH US).
Consensus expects adjusted EPS to rise from US$12.20 in FY25 to US$12.94 in FY26, US$13.73 in FY27, US$14.59 in FY28 and US$15.36 in FY29. Free cash flow is also expected to rise from roughly US$7.2bn to more than US$9bn over that period. That consistency comes from an exceptional franchise model, with recurring royalty and rental income, strong margins, high free-cash-flow conversion and relatively low earnings volatility.
The recent correction has also improved valuation, though this did look better a few weeks ago. Around US$280, MCD trades on ~21x forward earnings, below its five-year average closer to 23–24x, while offering a dividend yield of ~2.7%.
As suggested, the stock has already begun to recover after 3Q results came in better than the very weak expectations established at the Investor Day, while management has stepped up value initiatives aimed at bringing budget-conscious customers back through the door.
Ultimately, we are considering MCD as a potential defensive replacement for Ashland in the International Equities Portfolio. The recent pullback does reflect genuine near-term issues, including softer US traffic, affordability concerns and a larger investment program, but the underlying franchise remains one of the most consistent earnings compounders globally.
- With MCD trading on the cheaper side of history, earnings still trending higher and the share price recovering from its recent lows, retaining a constructive long-term trend, we think MCD is an attractive defensive option for the portfolio.