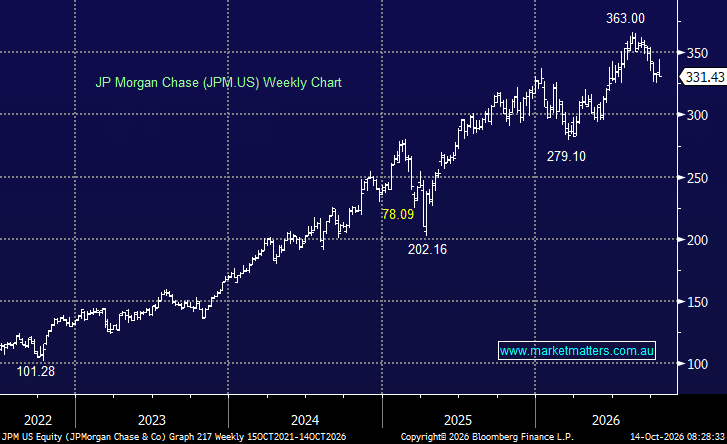
JPMorgan missed expectations mildly with stronger net interest income and equities trading largely offsetting a surprisingly weak result from fixed income.
3Q highlights;
- Revenue: US$50.17bn, up 8% YoY, missing consensus of US$51.23bn by 2%.
- EPS: US$5.57, up 10% YoY, missing consensus of US$5.94 by 6%.
- Net profit: US$15.3bn, missing consensus of US$16.2bn by 5.5%.
- Equities trading revenue: US$4.95bn, up 49% YoY.
- FICC trading: US$5.37bn, down 4% YoY.
- Investment banking fees: US$3.01bn, up 14% YoY.
The key positive was NII, with JPM lifting its FY26 forecast to around US$106.2bn from US$105.5bn previously. Loan growth also remains strong and credit quality was better than feared, with charge-offs below expectations. Fixed-income trading was the disappointment, falling for the first time in more than two yeas, while expenses are creeping higher – a theme across most of them.
Despite the miss, the core banking franchise remains extremely strong and we think JPM continues to demonstrate why it should command a premium valuation relative to peers. JPM is trading on 13.2x vs historical average of 12.3x, but was sold off during the session to close lower.