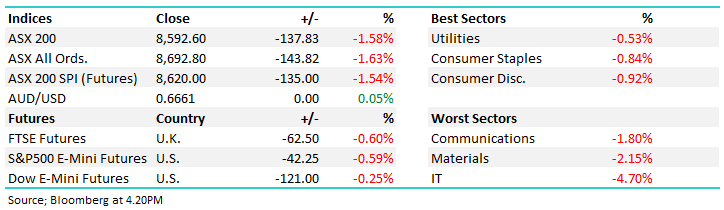
The ASX 200 was hammered ~500 points last week, or 5.4%, with only the defensive-facing utilities sector managing to advance. The week was dominated by fears around the AI infrastructure rollout not living up to expectations, hammering copper-facing stocks, with ASX heavyweights BHP (-12.7%) and RIO (-9.7%) tumbling accordingly. We also had a very weak employment report which showed Australia was at clear risk of a recession in 2027/8, sending bond yields lower but offering little support to risk assets.
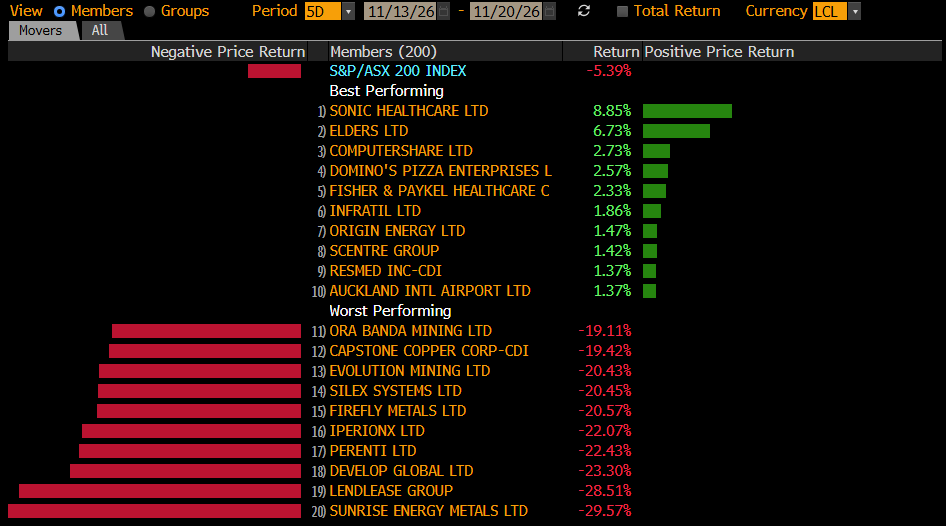
The best and worst-performing stocks last week illustrated the painful weakness across the ASX, with 8 stocks tumbling by over 20%, while only 2 managed to advance by more than 5%.
Winners: Sonic Healthcare (ASX: SHL) +9%, Elders Ltd (ASX: ELD) +7%, Computershare (ASX: CPU) +3%, Domino’s Pizza (ASX: DMP) +3%, Fisher & Paykel (ASX: FPH) +2%, Infratil (ASX: IFT) +2%, Origin Energy (ASX: ORG) +1%, and Scentre Group (ASX: SCG) +1%.
Losers: Sunrise Energy (ASX: SRL) -30%, Lendlease (ASX: LLC) -29%, Develop Global (ASX: DVP) -28%, Perenti (ASX: PRN) -22%, IperionX (ASX: IPX) -22%, FireFly (ASX: FFM) -21%, Silex Systems (ASX: SLX) -20%, and Evolution Mining (ASX: EVN) -20%.
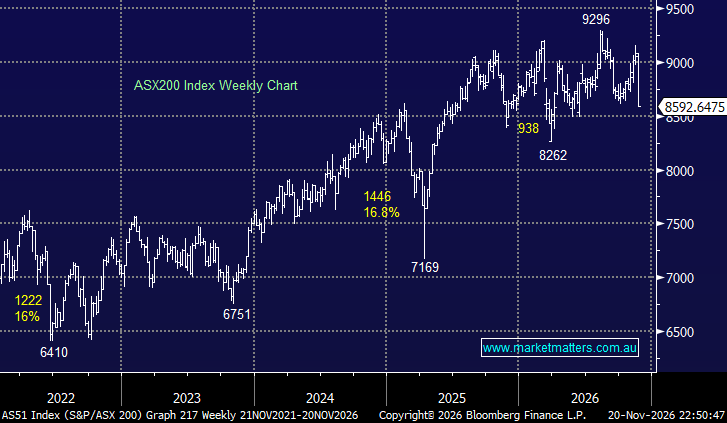
Weekly snapshot: The local market endured a tough week, which saw the ASX go from threatening new all-time highs to making fresh 5-month lows:
- The ASX 200 started the week on the back foot, with uncertainty around the AI trade and a renewed sell-off in resources weighing on the market.
- The local market was whacked 1.8% on Tuesday, with the global retreat in AI and technology stocks gaining momentum, while falling commodity prices delivered another blow to the resources sector.
- Wednesday delivered another soft session, with a fresh bout of AI uncertainty combining with a hawkish US Fed – Nvidia’s better-than-expected result failed to reverse the selling.
- Different day, similar outcome, with the ASX 200 just managing to avert triple-digit losses, with parts of the market supported by weaker-than-expected employment data triggering hopes for rate cuts in 2027.
- The ASX 200 ended the week with another triple-digit loss, extending its decline to 7 consecutive sessions, with tech and the miners leading the weakness.
Next week should, in theory, be quieter, but after this week, sentiment might remain the most important market driver:
Australia: The key domestic event this week is Wednesday’s October CPI release, which will be closely watched following last week’s employment shock (43,500 jobs lost and unemployment rising to 4.9%) and growing expectations of RBA rate cuts in 2027; however, sticky inflation could limit the Bank’s ability to ease. On the corporate front, AGM activity is relatively light, with the unwinding of the AI-driven metals rally likely to remain the main market focus.
US: The macro focus this week will be the October PCE inflation, the second estimate of Q3 GDP (consensus +3.6%), November flash PMIs and consumer confidence, against an increasingly hawkish Fed backdrop, with several officials signalling that further rate hikes may be necessary. On the corporate front, Dell Technologies is the major company left to report, with its AI-server revenue forecast to more than triple year-on-year, alongside results from HPE, Analog Devices and Deere; meanwhile, 86% of S&P 500 companies reporting have beaten EPS estimates, yet the market keeps falling.
- Technically, a test of March’s 8300 support level is looking likely, another 3-4% lower.
Overseas markets were again weak on Friday night, led by US tech as Anthropic (ANT US) fell over 10%. In Europe, the EURO STOXX 50 (-2.8%) and German DAX (-2.6%) both endured tough sessions. In the US, selling focused on tech stocks, with the NASDAQ tumbling 5.6% while the Dow, the best-performing major US index, retreated a relatively modest 1.9%.
- The SPI Futures are calling the ASX 200 to open down another 49pts/0.6% on Monday morning.