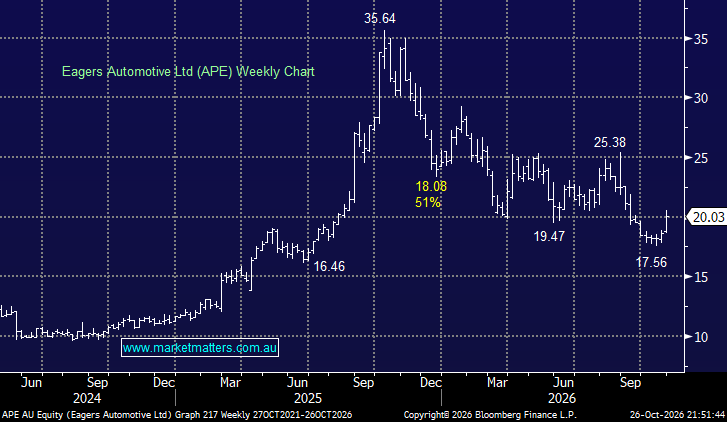
Eagers (APE) surged almost 8% yesterday after announcing it will acquire the remaining 20% stake in its BYD Retail Joint Venture, a deal expected to be immediately earnings accretive and to complete within days. The acquisition removes the minority partner and gives Eagers full ownership of the economics of its growing BYD dealership business. The expected earnings accretion (~5%) is a positive surprise, particularly after Eagers’ share price weakness over the past year, and provides a near-term tailwind for the stock.
- We already felt APE delivered a solid 1H26 result in August, with revenue rising 24% to $8.05bn and underlying operating profit before tax increasing 27% to $250.4m, around 10% ahead of expectations, but the stock has still fallen ~10% since.
APE has halved over the past 12 months despite earnings expected to grow by more than 10% pa between FY25 and FY27. The decline has largely reflected an unwind of the valuation premium built on expectations of sustained high growth. Even after Monday’s rally, the stock trades around 10% below its two-year average valuation. Over the last year, supply disruptions prevented Eagers from converting a record order book into bottom line earnings, prompting a sharp de-rating from a PE of 27x to around 15x. However, the underlying business remained operationally intact, with revenue growing, the BYD dealership network expanding and the CanadaOne acquisition completed. Monday’s announcement to buy out the remaining stake in its BYD joint venture, expected to be 5.0–5.5% accretive to underlying operating profit before tax, was enough to trigger a sharp rebound from oversold levels.
- Toyota: Production cuts and shortages of hybrids and large SUVs were the main constraint, with Toyota deliveries down around 20% in 1H26 despite order write-ups falling just 7%. The supply shortfall left Eagers unable to fulfil strong demand, with some customers switching brands rather than waiting months for delivery.
- BYD: A transition to its next-generation Blade Battery required production-line retooling, restricting vehicle output and extending delivery times to one or two months for affected models. Shipping capacity also constrained overseas deliveries, with the battery-related bottleneck now expected to ease by Q1 2027.
APE Eagers entered FY27 with an order bank of more than 25,000 units, a substantial revenue pipeline waiting to be converted. The improving (but not yet resolved) supply picture supports the view that earnings will improve moving forward, but the full benefit of order-bank conversion is more of a 2027 story – not too far away now.
Eagers is expanding its scale while maintaining momentum in its existing operations. CanadaOne adds a meaningful North American growth platform, while the core Australian and New Zealand business remains healthy. The BYD buyout is an additional positive. The group is also reshaping its portfolio, including plans to exit its franchised New Zealand dealership business while retaining easyauto123, and investing in premium automotive retail through its 50% investment in Zagame Group.
- We see good risk/reward towards APE with supply disruptions set to improve in early 2027, plus a ~3.8% fully franked dividend should help patient investors.
MM is bullish towards APE around $20
Add To Hit List