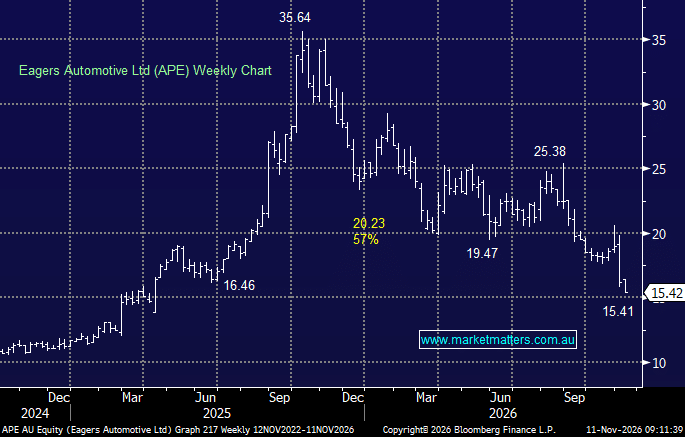
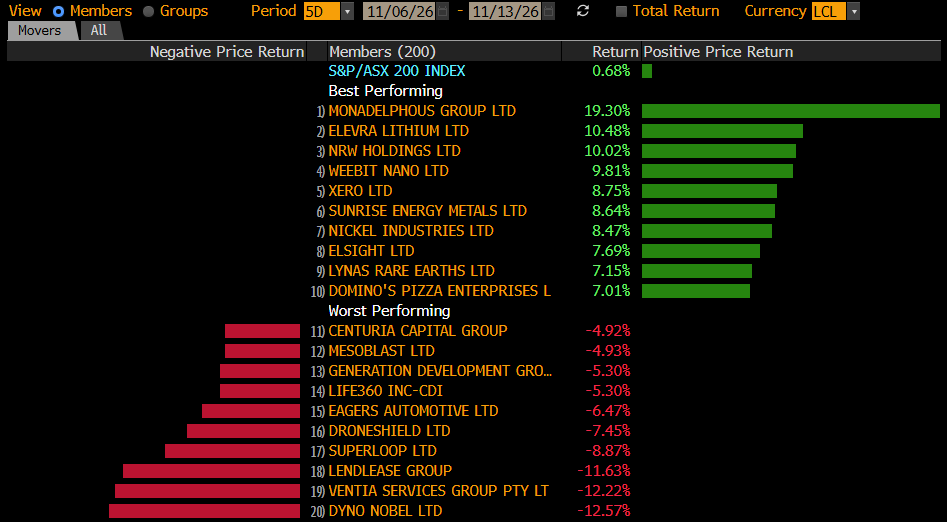
We only recently added Eagers Automotive (APE) to the Income Portfolio and unfortunately walked straight into an earnings downgrade. We initially viewed the subsequent sell-off as excessive given the quality of the business, strength of CanadaOne and continued growth from BYD, but the stock’s failure to recover is telling us something. The fundamental momentum has clearly deteriorated with consensus forward EPS cut by around 11%. When earnings revisions are confirmed by price, we need to reduce exposure.
The problem is primarily Australia, with higher interest rates, falling house prices and weaker consumer conditions weighing on vehicle demand, while the rapid shift from traditional internal-combustion vehicles towards EVs and Chinese manufacturers is creating additional pressure on dealer margins. UBS estimates APE’s core Australian Profit Before Tax (PBT) fell sharply in 2H26, with strong BYD sales masking considerably weaker conditions elsewhere in the portfolio.
October industry data reinforces that point. APE’s overall sales index rose 33% YoY, but this was driven by BYD, where volumes increased 153%. Excluding BYD, APE’s index was down 19% YoY, following declines of 17% in September and 15% in August.
The positive is CanadaOne, which is performing ahead of expectations, BYD remains a powerful growth driver and Eagers is arguably the best operator in the Australian dealership sector. Consensus also remains broadly positive, with nine Buy recommendations, five Holds and no Sells, while the average target price of ~$21.80 sits materially above the current share price.
However, price action matters when it confirms deteriorating fundamentals. APE failed to participate meaningfully in yesterday’s strong market and remains pinned near its lows. With earnings estimates moving lower, we’re reluctant to simply assume the bad news is now fully reflected in the price.
In a note by UBS, they cut forecasts for FY26 underlying EPS from $1.03 to $0.89 and FY27 from $1.22 to $1.05. The broker still expects earnings growth to resume from FY27, but that relies on an eventual cyclical recovery and margin improvement that is yet to appear.
We still like Eagers as a business and believe CanadaOne, BYD and its industry-leading position provide attractive longer-term growth opportunities. However, we bought into the stock just before the earnings outlook deteriorated, and the subsequent combination of negative revisions and weak price momentum argues for greater caution.
- Rather than waiting for a turnaround, we are going to reduce our position and lower portfolio risk. We can always rebuild the exposure when earnings revisions stabilise, and the share price starts to confirm that conditions are improving.
MM plans to reduce our position in APE in the Income Portfolio
Add To Hit List