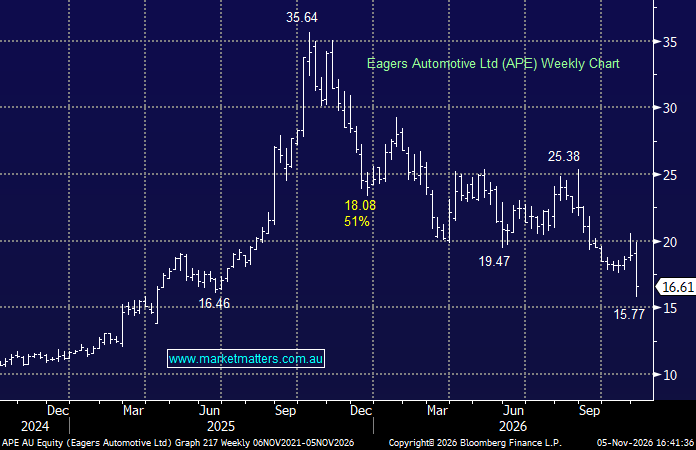
APE –13.22%: Was hit hard today after its trading update highlighted weaker Australian conditions and FY26 revenue guidance came in below expectations.
The headline numbers still look strong, although much of the growth reflects the expansion into Canada.
- FY26 revenue guidance: A$17.3–17.5bn, up at least 30% YoY, but below consensus of ~A$17.8bn – about 2.2% below
- Underlying return on sales: expected at 2.8–3.0%.
- Both revenue and underlying PBT are still expected to reach record levels in FY26.
- Australian Q3 trading was impacted by broader industry and macroeconomic headwinds.
- CanadaOne Auto continues to outperform, with Q3 ahead of expectations.
The key issue is the Australian business. Higher interest rates and cost-of-living pressures are increasingly weighing on consumers, and big-ticket discretionary purchases such as cars are an obvious place for households to pull back.
On the positive side, the Canadian acquisition is doing what Eagers hoped, providing another growth engine and reducing reliance on the Australian cycle. The 2.8–3.0% return-on-sales target also suggests margins remain reasonably resilient despite softer domestic volumes.
The reaction today was a big one, and excessive in our view for the mild top line downgrade, but stocks in this market are not performing on any incremental change to guidance/deterioration in trends. The position in the Income Portfolio will come under review if it fails to bounce.
MM views todays share price move as an overreaction
Add To Hit List