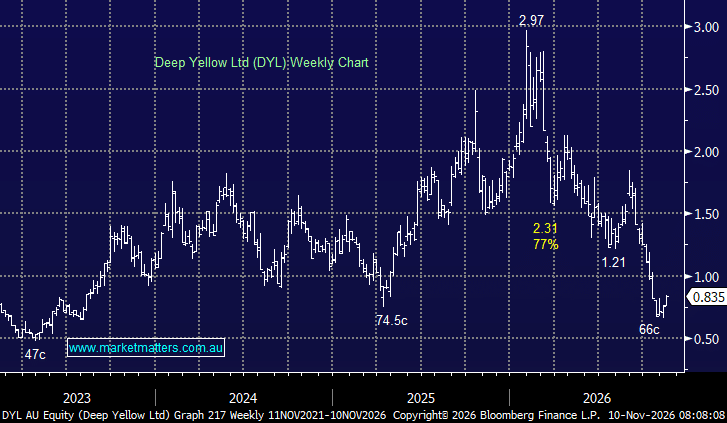
DYL has been a major underperformer in 2026, tumbling close to 80% as its Tumas project in Namibia doesn’t stack up at current uranium prices, and the market knows a dilutive equity raise is coming when it eventually is. The stock peaked in January when the market was pricing in $120–150/lb uranium; at $92.50/lb today, the project economics do not work, the FID has been delayed indefinitely, and investors are left holding a cash-burning developer facing further dilution. Until uranium spot sustainably clears ~$100/lb, the re-rating catalyst remains absent.
NB: We believe prices will climb above US$100/lb, but the logical time to buy DYL is post the inevitable capital raise.
- We can see a ~20% bounce by DYL, but we continue to prefer NXG in the early-stage uranium space.
MM is cautiously bullish towards DYL around 80c
Add To Hit List