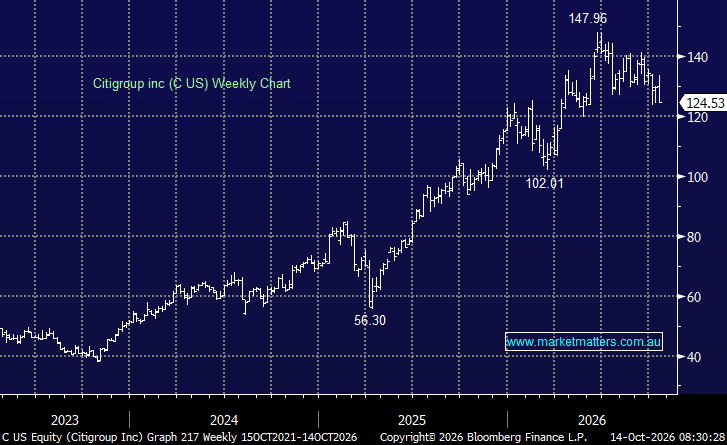
Citigroup delivered a better-than-expected quarter across most key metrics, including NII, credit and fixed-income trading, however they downplayed their return on capital target, and that’s what put the kibosh on the stock overnight.
3Q highlights;
- Revenue: US$23.85bn, up 8% YoY, beating consensus of US$23.72bn by 1%.
- EPS: US$2.85, up 53% YoY, beating consensus of US$2.65 by 8%.
- Net profit: US$5.25bn, beating consensus of US$4.94bn by 6.3%.
- Equities trading revenue: US$1.73bn vs US$1.73bn expected.
- FICC trading: US$4.39bn vs US$4.34bn expected.
- Investment banking revenue: US$1.35bn, up 9% YoY.
Citi’s fixed-income business delivered its best third quarter in at least a decade, while Services revenue rose strongly. Credit was also better than expected and management continues to target an efficiency ratio below 55% and medium-term RoTCE of 14–15%.
However, the shares fell sharply as management remained cautious around buybacks and indicated full-year RoTCE would finish only above 11% i.e. lower than hoped. Citi is clearly improving, but after a strong share-price run, there was not enough evidence that the restructuring can translate into sustainably higher returns. C is trading on 9.9x vs historical average of 10.4x, and was sold off ~5% overnight.
MM is neutral C US ~$US125
Add To Hit List