Broadcom operates two businesses: semiconductors and infrastructure software. Its semiconductor division designs custom AI processors (XPUs), networking chips and connectivity products, while its software division provides enterprise infrastructure, virtualisation and cybersecurity solutions, largely through its VMware acquisition.
Like most in the space, the numbers are impressive: In Q3 FY2026, Semiconductor Solutions generated US$20.8bn in revenue, including US$16.7bn from AI semiconductors, up 221% year-on-year. Infrastructure Software contributed US$8.75bn, with operating margins of approximately 84% and more than 90% of bookings recurring. The software business provides a valuable source of predictable, high-margin earnings alongside its more cyclical semiconductor operations.
Broadcom is an interesting alternative to NVIDIA because it benefits from a different part of the AI infrastructure boom. Rather than focusing on general-purpose GPUs, it designs custom AI accelerators (XPUs) for hyperscalers including Google, Meta, Anthropic and OpenAI. These companies are increasingly developing their own chips to reduce reliance on NVIDIA, improve efficiency and potentially lower computing costs. Broadcom also supplies the networking technology required to connect these chips into large AI clusters.
- Broadcom is a legitimate alternative to NVIDIA, and they could benefit if customers shift spending away from NVIDIA GPUs towards custom-designed AI chips. Broadcom is estimated to hold approximately 60–70% of the custom AI ASIC market, positioning it to capture a greater share of hyperscalers’ investment.
Broadcom offers a different way to play the AI infrastructure boom. If NVIDIA loses momentum because hyperscalers increasingly adopt custom-designed chips, Broadcom could be a significant beneficiary. However, if NVIDIA slows because the entire AI investment cycle is cooling, Broadcom will not be immune. Its high-margin, recurring software business provides some earnings protection but cannot fully offset a significant downturn in AI spending.
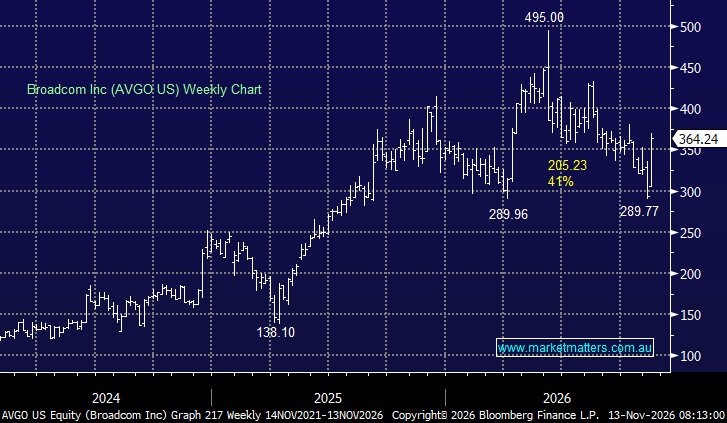
Overnight, AVGO rallied more than 5%, a sensible reaction in our view, and unlike most others in the space, AGVO is trading ~25% below Junes high, created reasonable risk/reward at current levels.
- We can see AVGO trading higher into 2027 with our initial target ~US$425.
MM is bullish towards AVGO around US$360
Add To Hit List