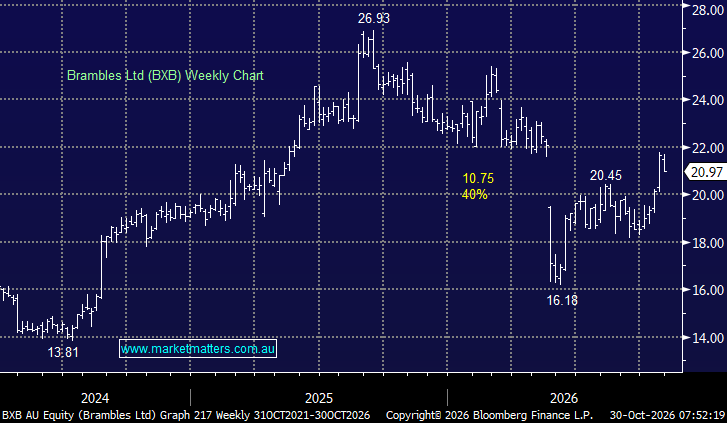
BXB has sat in MM’s Hitlist for a few months, always frustrating when the stock jumps ~10% but never say never! We like BXB as discussed earlier in the month here, but it has now reached our initial ~$22 target area. We believe the US pallet-repair constraints appear fixable rather than structural. FY26 underlying profit rose 4% despite a US$90m repair-related drag, implying around 11% growth excluding the disruption. Pallet quality is improving, repair capacity is being expanded by around 20% by FY28, and management expects the US earnings drag to ease in FY27.
However, the recovery still needs to be proven through execution. Longer term, AI-driven demand planning and Brambles’ Serialisation+ initiative should improve pallet availability, supply-chain visibility and operational efficiency, although the financial benefits are more likely from FY28 onwards. At current levels, the risk/reward has diminished, but we still like this turnaround story.
- We continue to like BXB but haven’t pressed the “Buy” button due to its correlation to Amcor (AMC), an existing holding.
MM is cautiously bullish toward BXB below $21
Add To Hit List