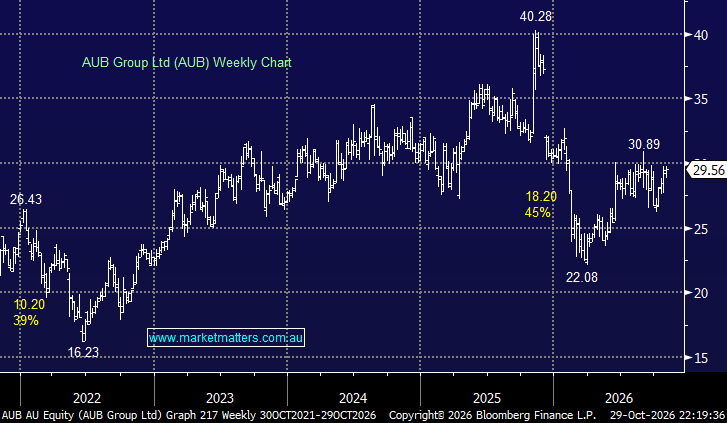
We are closer to calling the large ASX insurers like IAG a sell as opposed to a buy, but another 5% on the upside wouldn’t surprise. However, AUB is walking its own path; it was hammered in late 2025 following the collapse of EQT and CVC Asia’s $5.2 billion takeover bid at ~$45, sending the stock down ~18% in one day last December. Selling pressure intensified in February as fears that AI-powered platforms could disrupt insurance broking, pushing AUB to a March low. Sentiment has since improved, with AUB supported by renewed M&A interest after Steadfast received a takeover approach from Amwins and Dragoneer in June.
Importantly, the share-price decline has been driven more by valuation compression, with AUB trading ~20% below its 5-year valuation while revenue and earnings are expected to grow in FY27, delivering a solid risk/reward opportunity below $30, supported by an estimated 3.7% fully franked yield. Hence, we find AUB interesting below $30, with M&A gathering momentum across the ASX as the potential cream on the cake.
- We can see AUB initially testing $31 in the coming weeks.
MM is cautiously bullish towards AUB below $30
Add To Hit List