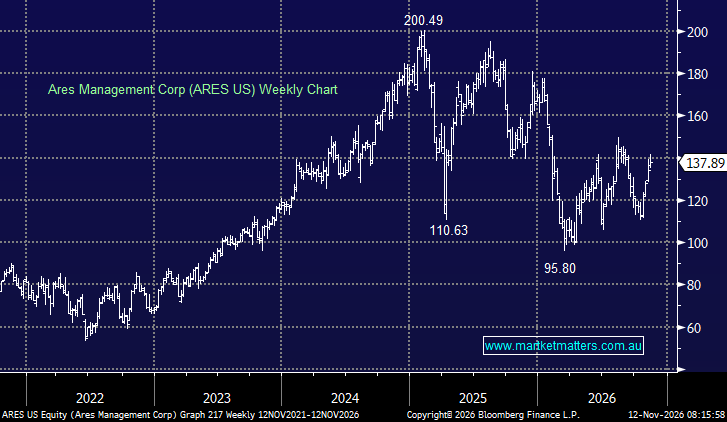
Ares Management (ARES US) is a very different business from the previous 3, operating as a large-scale alternative asset manager focused on private markets rather than traditional public equities – it only joined the S&P 500 last year. Its platform spans five areas, credit, real assets, secondaries, private equity and insurance, with credit the dominant division at US$446 billion, or approximately 65% of fee-earning assets.
A key attraction is the durability of its earnings, with 93% of management fees generated from perpetual-capital or long-dated funds, providing greater earnings visibility than traditional fund managers. Ares has also built a substantial presence in the wealth market, where its retail investment products generate three to four times the fee yield of comparable traditional drawdown funds. The business continues to grow strongly, with AUM reaching US$691 billion in Q3 2026, up 16% year-on-year, supported by US$28.6 billion in quarterly net inflows.
- However, the stock has softened of late as ARES has disappointed with its AUM conversion into fees.
The attraction to ARES centres on its scale, diversified private-markets exposure and relatively predictable management-fee income, complemented by additional performance-related revenues. Fee-related earnings (FRE) grew to US$2.07 billion in 2026, with the FRE margin reaching 42.5% in Q3, while management fees remain the primary earnings driver. Performance has also been solid across credit and real assets, although secondaries and private equity have been softer.
There are risks, however, particularly around the pace of capital deployment, the timing of performance-fee realisations and liquidity pressures in private credit, highlighted by the decision to cap withdrawals from its Ares Strategic Income Fund in March 2026.
- ARES is trading ~20% below its average 2-year valuation, with private credit concerns one catalyst but the core reason ARES looks cheap is that the market simply stopped paying 50x FRE for alt managers. The business quality hasn’t deteriorated; the price paid for that quality has simply reset materially lower, affording better risk/reward.
Compared with Regal, Ares operates at roughly 30 times the scale, with a substantially broader platform and more durable capital base. It is arguably the strongest structural business in this peer group, although its exposure to private credit and the growing popularity of semi-liquid retail products warrant monitoring.
- We can see ARES testing US$150-160 into 2027 after the sector’s downward re-rating.