- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
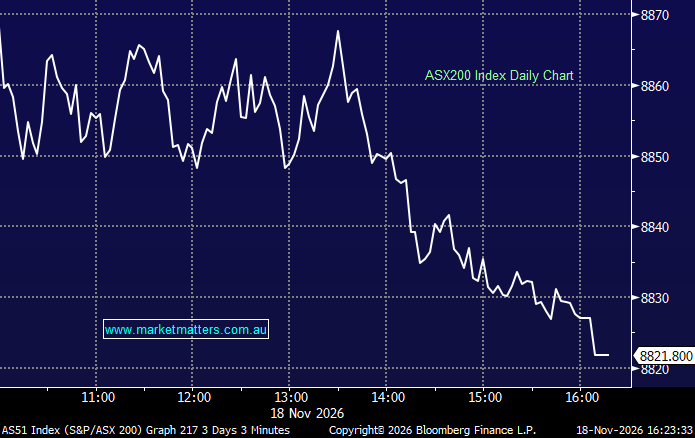
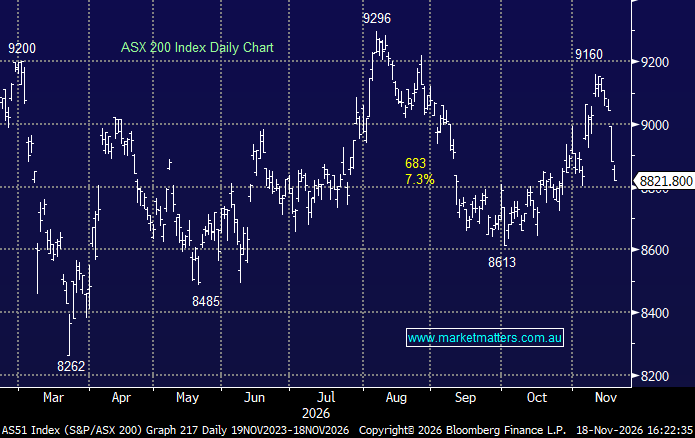
The Aussie share market extended its losing streak to five consecutive sessions as another bout of uncertainty around the AI trade, hawkish US Federal Reserve commentary and rising US rate expectations weighed on global sentiment. Nvidia’s better-than-expected result prior to our market open offered some reassurance around AI demand, but failed to reverse the broader retreat, while stronger-than-expected Australian wage growth data released this morning added another layer of pressure.
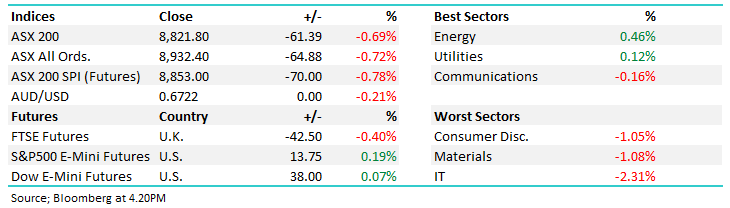
- ASX 200: 8,821.80, -61.39pts / -0.69%.
- AUD/USD: 0.6722, -0.21%.
- Best Sectors: Energy +0.46%, Utilities +0.12%, Communications -0.16%.
- Worst Sectors: Consumer Discretionary -1.05%, Materials -1.08%, Information Technology -2.31%.
- Rates and banks: Australian wages rose 1.1% in the September quarter, the strongest quarterly increase since late 2023, lifting annual growth to 3.5%. CBA economists said the result would keep the RBA on edge into early 2027.
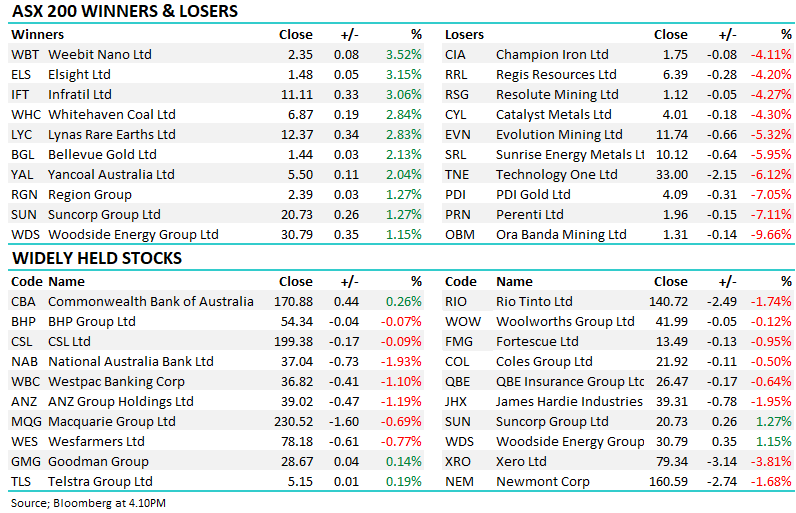
- The Big Four weighed on the index, with the exception of Commonwealth Bank of Australia (ASX: CBA) +0.26% to $170.88 which edged higher, National Australia Bank (ASX: NAB) -1.93% to $37.04, Westpac Banking Corporation (ASX: WBC) -1.10% to $36.82 and ANZ Group Holdings (ASX: ANZ) -1.19% to $39.02 all retreated. WBC & ANZ held in the Active Growth & Income Portfolios.
- Technology was the weakest sector as the global AI sell-off continued despite Nvidia beating quarterly revenue forecasts. Its third-quarter revenue reached US$115.8 billion, 5.9% above estimates, and its shares rose after hours. Jensen Huang said he would return if asked, but Nvidia’s board said it was not considering reinstating him.
- Tech stocks were broadly weaker with TechnologyOne (ASX: TNE) -6.12% to $33.00 giving back much of yesterday’s gains after its stellar result while Xero (ASX: XRO) -3.81% to $79.34 also fell. XRO held in the Active Growth Portfolio.
- Materials turned lower after miners’ early rebound faded. Iron ore was trading near a four-year low as China’s state-backed buyer tightened its influence over supply negotiations. Chinese analysts said prices may need to fall towards US$80 a tonne before high-cost mines cut output.
- BHP Group (ASX: BHP) -0.07% to $54.34, .Rio Tinto (ASX: RIO) -1.74% to $140.72 and Fortescue (ASX: FMG) -0.95% to $13.49 all declined. BHP & RIO held in the Active Growth & Income Portfolios.
- Bullion fell to a 14-month low as markets priced in further US rate rises, and gold miners gave back their early gains – Newmont Corporation (ASX: NEM) -1.68% to $160.59 and Evolution Mining (ASX: EVN) -5.32% to $11.74 were among those hit.
- Energy stocks were solid with Whitehaven Coal (ASX: WHC) +2.84% to $6.87 and Woodside Energy Group (ASX: WDS) +1.15% to $30.79 higher. WHC held in the Active Growth Portfolio.
- Infratil (ASX: IFT) +3.06% to $11.11 lifted FY27 EBITDAF guidance as data-centre and renewable capacity came online. CDC’s EBITDAF rose 84% to A$339 million, with contracted capacity reaching 1.1GW.
- Lendlease Group (ASX: LLC) -16.91% to $1.72 remained under pressure after Morgan Stanley downgraded the builder from equal weight to underweight.
- PEXA Group (ASX: PXA) -2.48% to $6.69 fell after NSW’s pricing regulator recommended a 16% cut to regulated exchange revenue from FY28, an estimated annual revenue impact of about $50 million, though better than the expected ~16% – the review is to be formalised by the end of CY27.
- SEEK (ASX: SEK) -1.81% to $13.53 received a first strike on its remuneration report, with 35% of investors voting against it. The company reaffirmed FY27 guidance, including midpoint adjusted profit of $200 million, while job-ad volumes in Australia and New Zealand were tracking lower.
- Gold: Traded near US$3,795/oz / -1.5%.
- Iron Ore: US$88/mt / +0.6%.
- Brent crude: US$92.50/bbl / -0.6%.
- Futures: S&P 500 E-mini futures +13.75pts / +0.19% | Dow Jones futures +38.00pts / +0.07% | FTSE futures -42.50pts / -0.40%.