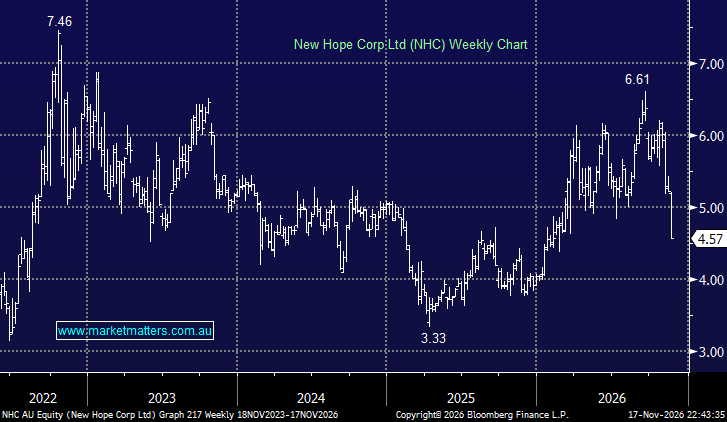
It’s been 20 years since we’ve seen a new corporate hybrid poised to list on the ASX, and this week New Hope, a company we own shares in, has launched one. Our thoughts/analysis outlined below, noting the bookbuild is now open to wholesale investors only, and is available through Market Partners for qualifying investors ([email protected])
NHC is looking to raise A$250m via an ASX-listed perpetual hybrid, expected to trade under the code NHCHA. Feedback from management yesterday is that demand has been strong, and we’re hearing the same thing directly from the book runners, though not surprised by the latter.
The securities are expected to pay a floating distribution of 3-month BBSW +4.0%, fully franked, paid quarterly. Based on current rates, this is an indicative gross running yield of ~8.9% (i.e. inclusive of franking). The securities are perpetual, but with a significant 5% margin step-up from December 2031 if they remain outstanding, implying that NHC are highly incentivised to redeem them in 5 years. In other words, if not redeemed in 5 years the margin becomes 9% + BBSW. Separately, if a Change of Control Event occurs and NHC doesn’t redeem, the Margin increases by a further 5%. These two step-ups are cumulative, so in the worst case (step-up date passed and a change of control, neither redeemed) the margin could reach ~14% over BBSW.
A few things make the transaction interesting. Firstly, NHC has around A$700m of accumulated franking credits, and the hybrid provides an efficient way to begin monetising that balance through fully franked distributions. This is particularly relevant as the traditional bank hybrid market progressively contracts.
Secondly, NHC enters the transaction with a very strong balance sheet. Its only material parent-level debt is A$300m of senior unsecured convertible notes due in 2032, carrying a coupon of 2.625%. The new hybrids will sit below those convertible notes and other senior creditors in the capital structure, but ahead of ordinary equity.
The timing also links directly to NHC’s proposed acquisition of Malabar Resources. Malabar currently carries relatively expensive financing, with some debt costing around 16%. If Malabar shareholders approve the transaction, NHC intends to use the proceeds from the hybrid issue to repay or refinance part of Malabar’s existing debt facilities, which sit around ~$700m.
Post the hybrid issue and assumed completion of the Malabar acquisition, the pro forma position is:
- Borrowings: A$913.7m
- Cash: A$792.8m
- Net debt on a cash-only basis: A$120.9m
- Managed funds / other financial assets: A$293.8m
- Total liquidity: A$1.087bn
- Net leverage: only 0.2x FY26 EBITDA
Meaning A$120.9m of net debt post-hybrid and post-Malabar. Also worth mentioning that Soul Patts (ASX: SOL) holds about 39% of New Hope.
The economics of the transaction makes sense in our view. NHC can raise subordinated capital, utilise its substantial franking credit balance and use the proceeds to replace very expensive debt sitting within Malabar (assuming the deal goes through).
BondAdviser has put a Subscribe recommendation on the issue while noting that it is a high-risk security. In terms of the risks we see, the key ones include the securities being perpetual (but the step up addresses that in our view), subordinated and unsecured, ranking behind NHC’s A$300m convertible notes. Distributions are also discretionary which is the case generally in Hybrids, although any deferred amounts accumulate and compound. Further, they cannot pay a dividend on the shares if they don’t pay one on the hybrids (there is a 20-day grace period here), and in the event the Step-up Date (15 Dec 2031) has passed and the hybrids haven’t been redeemed, the dividend stopper kicks in and they can’t pay ordinary dividends.
The additional fine print is very much aligned with current hybrids on issue, although there is not a non-viability or conversion trigger because the securities are not considered regulatory capital as they are with the banks. Relative to other similar sorts of perpetual securities, the step-up rate is also more generous (i.e. investor friendly)
The biggest fundamental risk remains NHC’s exposure to thermal coal, while completion and integration of Malabar adds execution risk. That said, the balance sheet remains very strong, and the 5% step-up is additional to the initial 4% margin provides NHC with a very strong economic incentive to redeem them before or around that date.
- Overall, we think this is a solid issue for investors comfortable with the subordinated nature of the security and NHC’s underlying thermal coal exposure. Strong early demand suggests the market is thinking along similar lines.
If you would like to bid into the bookbuild, email p[email protected]. This invitation is restricted to eligible wholesale investors. Wholesale investor status must be verified before any participation can be considered. Expressions of interest do not constitute applications or guarantee an allocation. Investors should review the prospectus and associated risk factors before making any investment decision.
View the NHC Hybrid Securities Prospectus
If you qualify as a wholesale investor and would like further information, please contact the Market Partners team (02) 9188 4964. Market Matters and Market Partners provide general information only in this communication. It does not take account of your personal financial circumstances, objectives or needs.