- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
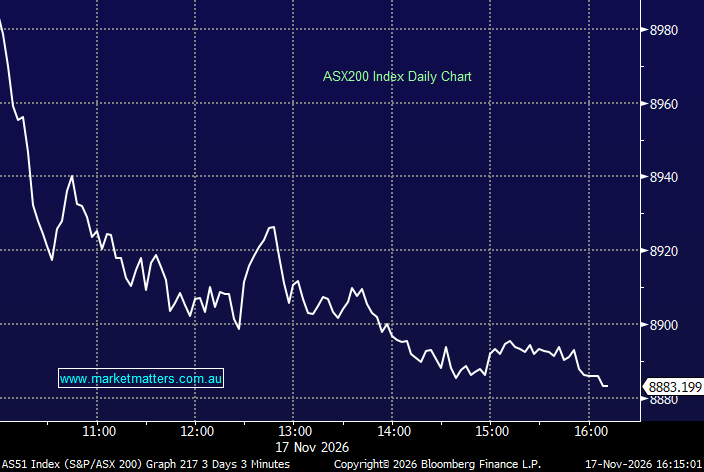
Aussie shares suffered a tough day today, declining for a fourth consecutive session, as the global retreat in AI and technology stocks gathered pace, while falling commodity prices delivered a blow to the resources sector. The weakness was broad-based, with investors cutting risk ahead of Nvidia’s earnings result tomorrow morning, as well as reacting to tighter US restrictions on China’s access to advanced AI chips.
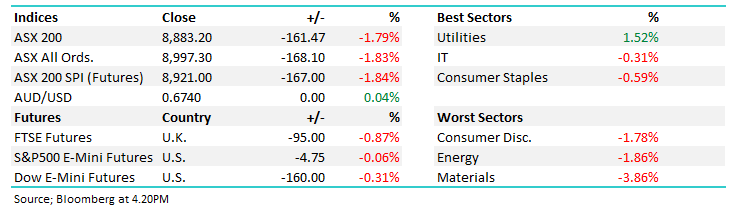
- ASX 200: Closed at 8,883.20, -161.47pts, -1.79%.
- AUD/USD: 0.6740, +0.04%.
- Best Sectors: Utilities +1.52%, Information Technology -0.31%, Consumer Staples -0.59%.
- Worst Sectors: Consumer Discretionary -1.78%, Energy -1.86%, Materials -3.86%.
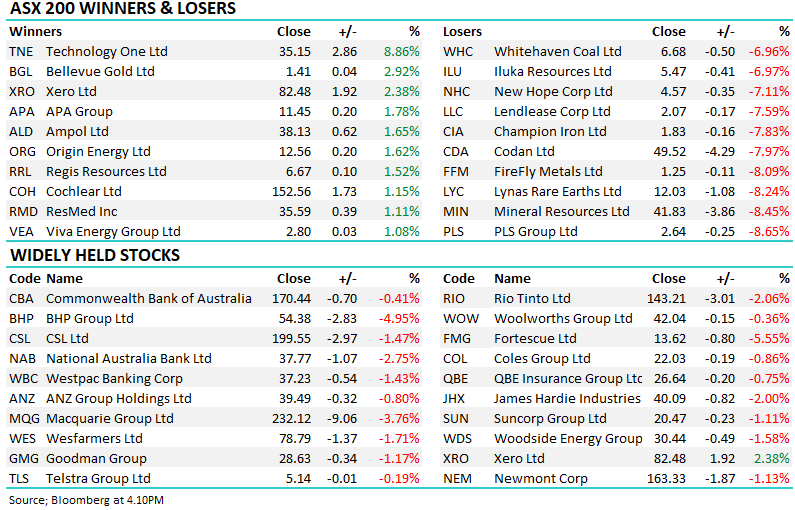
- Materials bore the brunt of the local selling, as weakness across iron ore, copper, lithium, uranium and rare earths weighed heavily on miners. BHP (ASX: BHP) -4.95% to $54.38 and Rio Tinto (ASX: RIO) -2.06% to $143.21 led the weakness among the major diversified miners, with iron ore remaining below US$90 a tonne and copper slipping to a four-month low in London. BHP & RIO held in the Active Growth & Income Portfolios.
- Mineral Resources (ASX: MIN) -8.45% to $41.83 and PLS Group (ASX: PLS) -8.65% to $2.64 were among the hardest-hit lithium names, while other resources stocks Lynas Rare Earths (ASX: LYC) -8.24% to $12.03 and FireFly Metals (ASX: FFM) -8.09% to $1.25 also suffered sizeable declines.
- Energy stocks remained under pressure after Brent crude fell overnight on expectations of a global supply surplus, despite renewed attacks in the Strait of Hormuz. The International Energy Agency sees fourth-quarter supply running around 1.7 million barrels a day ahead of forecast demand, while weaker Chinese refinery throughput added to concerns around consumption.
- Whitehaven Coal (ASX: WHC) -6.96% to $6.68 and New Hope Corporation (ASX: NHC) -7.11% to $4.57 were among the weaker energy names. WHC held in the Active Income Portfolio, NHC held in the Active Income Portfolio.
- Utilities names were the rare bright spot today, with Origin Energy (ASX: ORG) +1.62% to $12.56 and AGL Energy (ASX: AGL) +0.44% to $9.15 finishing higher. AGL held in the Active Income Portfolio.
- Financials struggled as National Australia Bank (ASX: NAB) -2.75% to $37.77, Westpac (ASX: WBC) -1.43% to $37.23 and ANZ Group (ASX: ANZ) -0.80% to $39.49 finished lower, while Commonwealth Bank (ASX: CBA) -0.41% to $170.44 proved comparatively resilient. WBC & ANZ held in the Active Growth & Income Portfolios.
- Technology was another area of weakness globally, although local performance was more mixed – Xero (ASX: XRO) +2.38% to $82.48 and Life360 (ASX: 360) +0.74% to $21.83 finished up while Wisetech (ASX: WTC) -0.19% to $47.31 moved lower. XRO & WTC held in the Active Growth Portfolio. 360 held in the Emerging Companies Portfolio.
- TechnologyOne (ASX: TNE) +8.86% to $35.15 bucked the trend after delivering its FY26 result at the top end of guidance – annual recurring revenue rose 18% to $652.1m, revenue increased 12% to $680.8m and EBITDA climbed 19% to $304.3m.
- Eagers Automotive (ASX: APE) -2.08% to $14.59 initially traded higher but faded through the day after announcing its entry into the U.S. automotive retail market, agreeing to acquire a multi-franchise dealership group in California representing Toyota, Honda and Volkswagen franchises. The acquisition will be undertaken via a new joint venture, with Eagers holding a 65% stake alongside Canadian auto entrepreneur Pat Priestner.
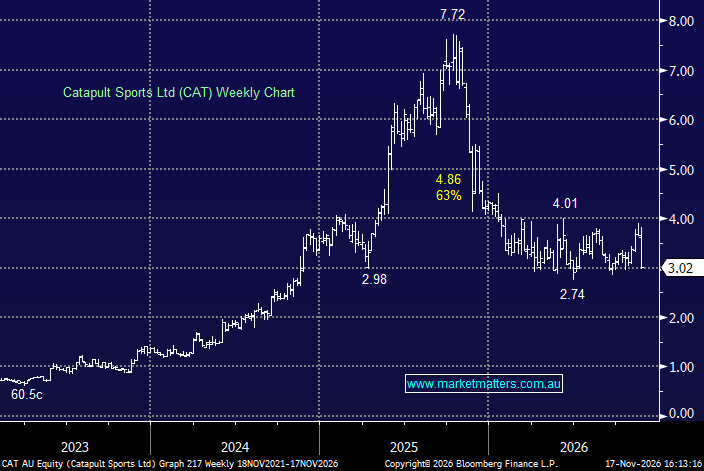
- Catapult Sports (ASX: CAT) -16.57% to $3.02 posted a weaker than expected 1H27 result with solid headline growth but missing consensus expectations.
- NextDC (ASX: NXT) -5.3% to $9.30 and Megaport (ASX: MP1) -6.62% to $16.78 were among AI infrastructure-linked names remained under pressure amid concerns about exuberant valuations and the sustainability of data centre investment. Macquarie Asset Management warned that some investors were paying elevated prices for AI exposure, despite its view that the longer-term infrastructure investment cycle remains intact.
- Perenti (ASX: PRN) -0.47% to $2.11 secured a five-year contract renewal worth approximately $1bn to continue operating at AngloGold Ashanti’s Geita Gold Mine in Tanzania, with the agreement running through to October 2031.
- PDI Gold (ASX: PDI) -0.45% to $4.40 received the final key exploitation permits for its Bankan project in Guinea, clearing a major hurdle ahead of planned construction and first gold production targeted for mid-2028.
- Regis Healthcare (ASX: REG) -5.88% to $4.80 flagged lower refundable accommodation deposit inflows as softer property market conditions influence resident payment choices, while government funding growth of 2.55% remains well below sector cost inflation.
- Wesfarmers (ASX: WES) -1.71% to $78.79 was also in focus after Bunnings announced it would cut 350 technology roles as part of a new arrangement with Tata Consultancy Services. The changes include around 230 permanent technology redundancies and the end of approximately 120 contractor engagements, with the work to be redeployed across TCS teams in India, the Philippines and Australia.
- Gold: Traded near US$3,894/oz / +0.7%.
- Iron Ore: $US87.60 / -0.4%
- Brent crude: $US91.70 / -0.8%
- Futures: S&P 500 E-mini futures -4.75pts / -0.06% | Dow Jones futures -160.00pts / -0.31% | FTSE futures -95.00pts / -0.87%.