Why SmartGroup (ASX: SIQ) is trading down ~9%
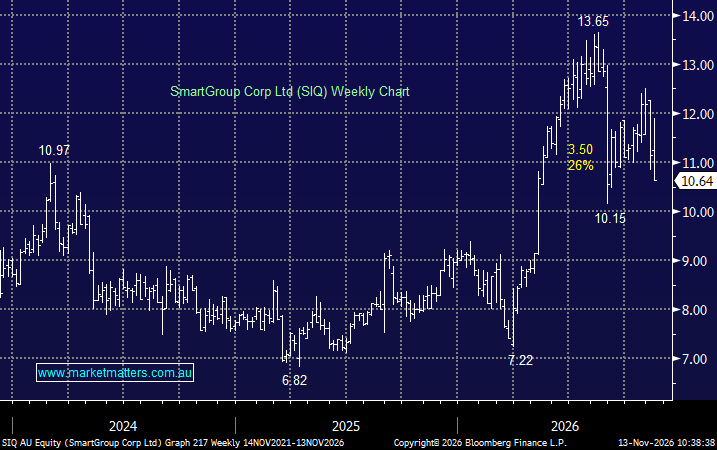
SmartGroup (ASX: SIQ) has come under sustained selling pressure, falling another ~9% today after slipping yesterday following 2026 full-year profit guidance issued at the UBS Australasia conference on Sunday.
- They guided to CY26 underlying net profit (NPATA) of $92–94m but indicated second-half EBITDA margins would remain broadly in line with the first half.
Third-quarter novated leasing orders jumped 33% excluding refinanced leases, investors appear disappointed that strong demand isn’t translating into improving margins, particularly following the stock’s impressive rally over the past year.
The market’s reaction looks more like a valuation reset than a deterioration in the underlying business. Management is deliberately accelerating investment in technology and operations, holding back near-term margins while maintaining its target of mid-40% EBITDA margins during 2027.
Despite the recent weakness, SIQ remains up ~40% over 12 months, suggesting expectations had become stretched.
- We believe the underlying growth story remains attractive, but delivering the promised margin expansion in 2027 will be critical to restoring confidence and supporting a sustained share price recovery.
MM is cautiously bullish below $11.