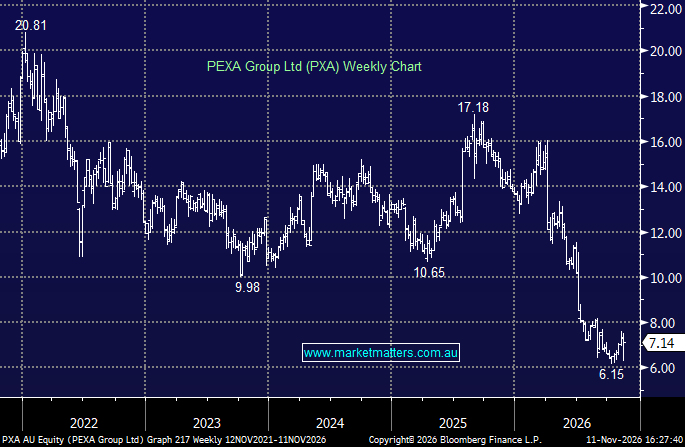
PXA -3.38%: cut its FY27 revenue and earnings margin guidance as falling property transaction volumes continue to weigh on its Australian business. The downgrade reflects a tougher housing market, with higher interest rates and declining property prices reducing buyer confidence and settlement activity.
Key details:
- FY27 revenue guidance reduced to $355m–$380m, from $385m–$415m.
- Core EBITDA margin guidance cut to 29–31.5%, from 31.5–33.5%.
- Core net profit guidance now ranges from a $6m loss to a $6m profit.
- First-quarter total exchange volumes fell 11.5% year-on-year, while transfer volumes declined 15.2%.
- October transfer volumes were down 26% year-on-year, while remortgage volumes were broadly flat.
- Capital expenditure guidance narrowed to $45m–$50m, from $45m–$55m.
This is a disappointing downgrade, with the weaker property market having a more meaningful impact on PXA’s earnings outlook. The October transfer volume decline of 26% suggests conditions have deteriorated further since the first quarter, making the near-term outlook challenging. Management is focusing on cost control to protect margins, while the upcoming NatWest transaction provides a potential longer-term growth opportunity. Australian property activity remains under pressure, though with the next RBA move now likely a cut instead of a hike, we see room for a turnaround in the medium term for PXA with volumes likely to stabilise and rise from here.
MM is long and cautiously bullish toward PXA
Add To Hit List