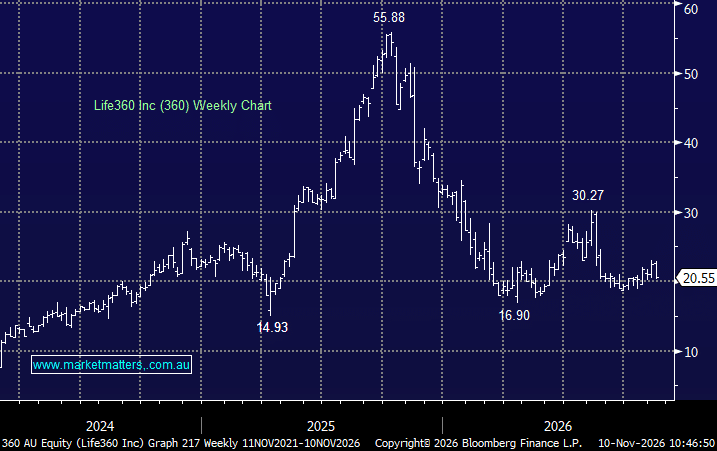
Why is Life360 (ASX: 360) down ~9%
Life360 (ASX: 360) is trading down fallen around 9% following its Q3 FY26 result, with investors disappointed by softer guidance despite earnings beating expectations.
- Revenue of US$174.1m exceeded consensus of US$171.4m, while EPS of US$0.26 also beat forecasts.
However, FY26 revenue guidance was narrowed to US$665–681m, broadly in line with expectations, rather than upgraded.
- More concerning was the reduction in advertising revenue guidance to US$98–102m from US$98–115m, alongside a modest cut to hardware revenue expectations.
Adjusted EBITDA guidance was also tightened to US$132–138m, leaving the midpoint unchanged at US$135m. The stock fell 8.5% in US trading, with the weakness flowing through to the ASX today.
The market’s reaction reflects disappointment with the outlook rather than the underlying quarterly performance. Advertising is an important higher-margin growth opportunity for Life360, making the guidance downgrade particularly unwelcome, while the lack of an earnings upgrade suggests much of the good news was already priced in.
However, some analysts remain constructive, highlighting stronger subscription revenue, encouraging user growth and the potential for EBITDA guidance to prove conservative.
- The key question is whether improving subscription margins can offset slower advertising growth and restore confidence in Life360’s earnings trajectory.
We are holding 360 in our Emerging Companies Portfolio with the position under review.