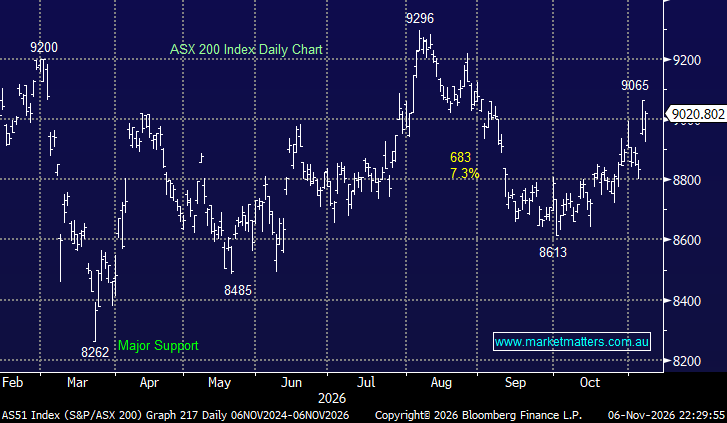
The RBA and US midterms drove a volatile week for the ASX 200, which ultimately finished up a solid 1.3%. Not a bad result given the uncertainty across some sectors after a blue wave of discontent washed through the US. Except for the energy sector, most pockets of the ASX contributed to the market’s close back above the psychological 9000 level, with a 10% gain by the software names, the standout. Rate-sensitive stocks enjoyed a strong week following the RBA’s almost dovish rate hike, with retail names like JB Hi-Fi and Harvey Norman advancing between +6 and +8%, while real estate names were also strong best demonstrated by Mirvac and Dexus advancing more than +5%.
Last week’s best and worst performers were an eclectic bunch. The Trump trade, particularly coal and defence, struggled, while software stocks and some of the market’s most beaten-up names led the gains.
Winners: NEXTDC (ASX: NXT) +77%, Nine Entertainment (ASX: NEC) +22%, Ora Banda Mining (ASX: OBM) +15%, Neuren Pharma (+14%), Xero (ASX: XRO) +14%, Block (XYZ) +14%, Zip Co (ASX: ZIP) +13%, Lend Lease (ASX: LLC) +13%, and Nick Scali (ASX: NCK) +11%.
Losers: Elsight (ASX: ELS) -21%, Electro Optic Systems (ASX: EOS) -18%, Eagers Auto (ASX: APE) -14%, AMP Ltd (ASX: AMP) -13%, New Hope Corp (ASX: NHC) -11%, Silex Systems (ASX: SLX) -11%, Mesoblast (ASX: MSB) -10%, and Whitehaven Coal (ASX: WHC) -10%.
Weekly snapshot: The local market performed stoically last week, managing to advance while volatility reigned supreme across overseas markets:
- The ASX 200 started the week off in a cautious manner, but a decent result from Westpac helped support the index.
- The RBA hiked rates 0.25% on Cup Day, as was expected, but the market took the tightening in its stride, helped by somewhat dovish commentary from Michele Bullock.
- On Wednesday, before Americans went to the polls, the market adopted a defensive position, selling miners and buying the likes of utilities.
- Thursday saw a “1-in-250 day” event with the ASX 200 soaring over 200 points as global markets digested the Democrats’ emphatic win in the mid-terms and an ~8% plunge in oil prices.
- The local market slipped ~0.4% on Friday as the miners encountered some selling with the “AI Trade” continuing to unwind, but compared to the carnage on Wall Street with the Nasdaq down ~6% on Thursday night, it felt like a win.
- Friday’s stronger-than-expected US employment data increased the odds of a Fed Christmas rate hike to almost 80%, but the local market still looks set to rally on Monday.
Next week, should see a quieter market with the RBA and US midterms behind us:
US: The main event for US equities next week will be Wednesday’s October CPI release, hot on the heels of Friday’s stronger-than-expected jobs report, which showed unemployment at 4.1%. The robust employment data has reinforced expectations of a December Fed rate hike, with several Fed officials signalling that further tightening may be required. Adding to the mix is the ongoing AI and technology uncertainty following the Democrats’ midterm sweep, with concerns over potential AI regulation, data-centre restrictions and stretched valuations keeping sentiment fragile.
Australia: It is set to be a quieter week locally, with Westpac Consumer Confidence on Monday providing another read on household sentiment, which is likely to remain under pressure, not helped by last week’s 5th RBA rate hike in 2026. On the reporting front, we will hear from ANZ and Aristocrat, with further volatility expected post their releases. ANZ will be watched especially carefully following NABs soft result this past week.
Overseas markets were mixed overnight as some calm returned to the chip stocks. In Europe, the German DAX (-1.9%) and UK FTSE (-1%) were weak as sentiment soured post the mid-terms. In the US, a recovery by the chip giants, which gained ~4%, helped the S&P 500 (+0.3%) and NASDAQ (+1.4%) to recover a small portion of their recent losses although the hot employment data didn’t help the broader market.
- The SPI Futures are calling the ASX 200 to open up +0.2%, recovering the losses on Friday after a steady session on Wall Street.