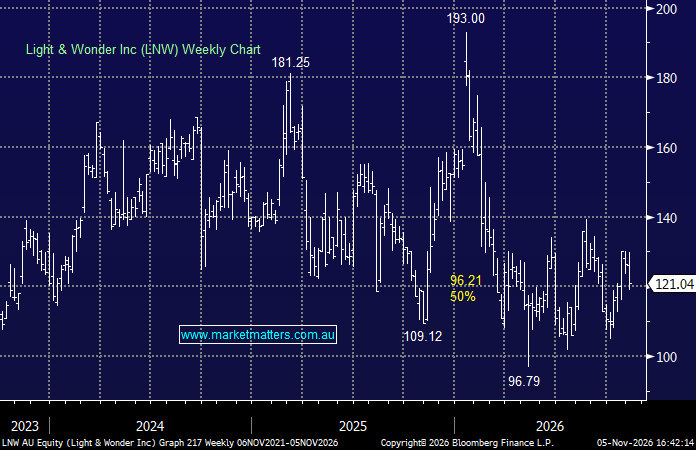
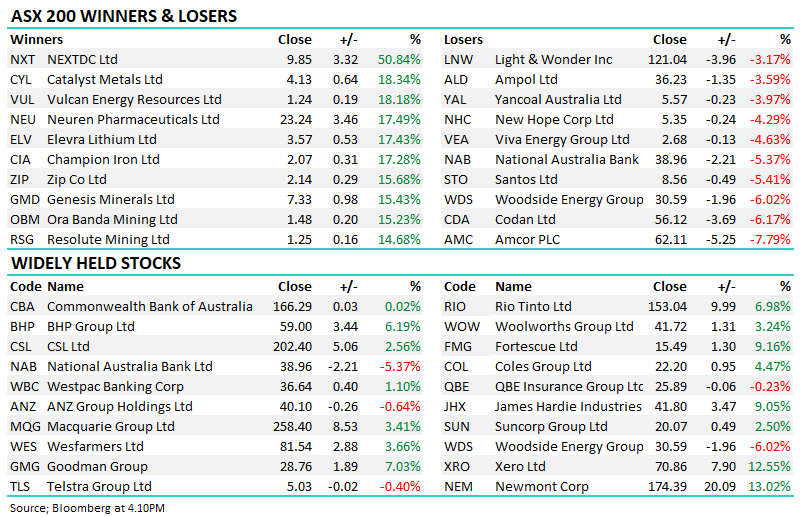
LNW –3.17%: Reported a softer-than-expected 3Q result, with revenue missing consensus across its Gaming and SciPlay divisions. The share price was weaker early but showed resilience, suggesting investors were relatively comfortable with the reaffirmed outlook.
Key details:
- Revenue of US$824m, below consensus of US$847.5m.
- Adjusted EBITDA of US$383m, slightly below expectations of US$387m.
- Gaming EBITDA rose 2% to US$312m, marginally ahead of estimates.
- SciPlay revenue declined 12%, reflecting weakness in the social casino market.
- FY26 EBITDA growth expected towards the lower end of the previous mid-to-high single-digit guidance range.
While the revenue miss and softer SciPlay performance highlight some near-term challenges, Gaming EBITDA remained resilient. With potential relief for consumers as rate hikes appear to be nearing a peak, we see scope for improved discretionary spending to support gaming demand. All things considered, we remain comfortable holding LNW in our Active Growth Portfolio, with the maintained outlook and resilient Gaming performance it looks well positioned to deliver on full year guidance.
MM remains long and bullish LNW
Add To Hit List