- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
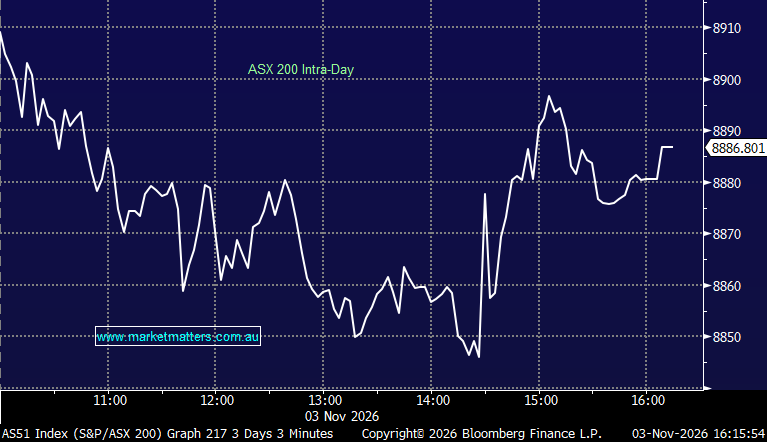
The ASX ultimately finished Melbourne Cup Day higher, but it was was struggling into the RBA decision, trading down around ~40 points, before rallying after the Bank delivered the widely expected 25bp hike. The split 6-3 vote, together with a more balanced message from Governor Michele Bullock, was enough to encourage buyers back into rate-sensitive parts of the market, particularly property and consumer stocks.
There was plenty of rotation underneath the index. REITs were the standout, while consumer discretionary and communications also performed strongly. Energy was hammered after oil fell sharply overnight, with coal, uranium and conventional energy names featuring heavily among the losers. Importantly, the market’s response to the RBA suggests investors are starting to look through the tightening cycle toward the point where higher rates begin doing enough damage to demand that further increases become unnecessary – more on this concept below.
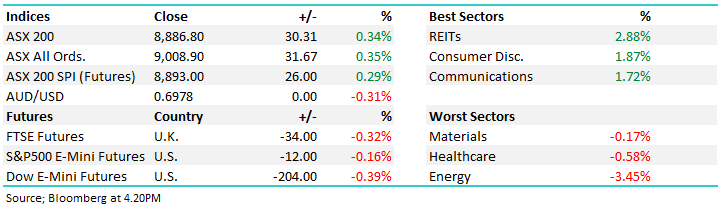
- ASX 200: +30.31pts / +0.34% to 8,886.80
- AUD/USD: 0.6978 / -0.31%
- Best sectors: REITs +2.88%, Consumer Discretionary +1.87%, Communications +1.72%
- Worst sectors: Energy -3.45%, Healthcare -0.58%, Materials -0.17%
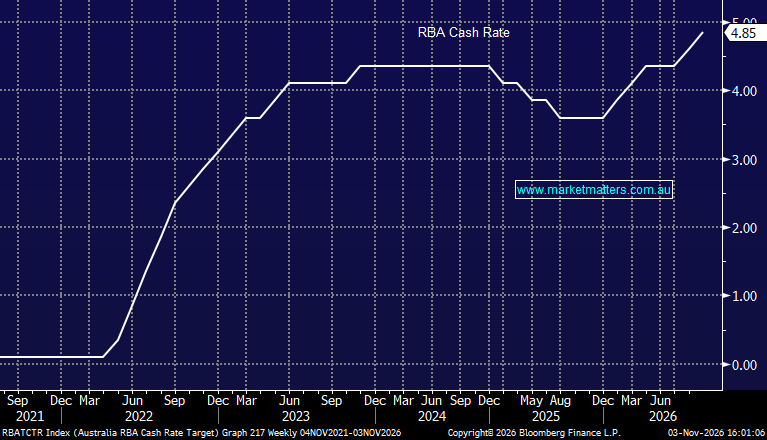
- RBA: The cash rate was lifted 25bp to 4.85%, an 18-year high, but the decision was only carried 6-3. Bullock stressed that several recent hikes are yet to fully flow through the economy and said she does not know what the next move will be. The market took the split vote and change in language relatively positively, with equities rallying after the announcement.
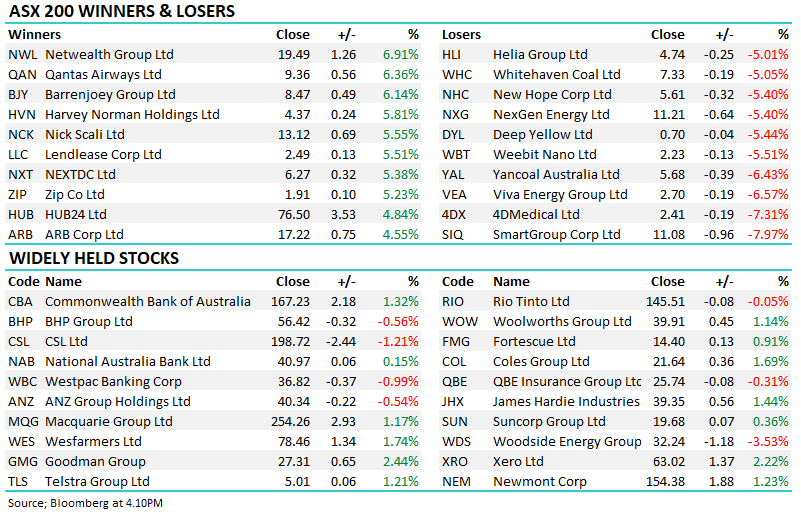
- Property was the clear beneficiary, with REITs up 2.88% as investors took some comfort from the possibility that the RBA is approaching the top of the tightening cycle. Goodman Group (GMG) +2.44% to $27.31, while a number of listed property names rallied 3–4%. We hold GMG in the Growth Portfolio.
- Consumer stocks also performed well, with Harvey Norman (HVN) +5.81% to $4.37, Nick Scali (NCK) +5.55% to $13.12, Flight Centre (FLT) +4.27%, JB Hi-Fi (JBH) +3.09% to $75.15 and Wesfarmers (WES) +1.74% to $78.46. We hold JBH in the Growth Portfolio & NCK in the Emerging Companies Portfolio.
- Netwealth (NWL) +6.91% to $19.49 topped the ASX 200, while HUB24 (HUB) +4.84% to $76.50 also rallied strongly given their high Beta to the market. We hold HUB in the Growth Portfolio.
- Qantas (QAN) +6.36% to $9.36 was another standout as the sharp overnight fall in oil improved the outlook for fuel costs.
- Technology bounced in selected areas, with NEXTDC (NXT) +5.38% to $6.27, ZIP (ZIP) +5.23% to $1.91, WiseTech (WTC) +3.23% and Xero (XRO) +2.22% to $63.02 all higher. We hold WTC & XRO in the Growth Portfolio, ZIP in the Emerging Companies Portfolio.
- AMP Ltd (ASX: AMP) -9.36% to $2.13 continued to slide after UBS cut earnings forecasts, following signs of slowing profit growth at China Life Pension Company, its 19.99%-owned Chinese pension partnership. UBS lowered FY26 and FY27 EPS forecasts by 4.6% and 4.8%, respectively, and retained Neutral.
- Barrenjoey Group Ltd (ASX: BJY) +6.14% to $8.47, the old Magellan was among the session’s strongest performers.
- Energy was the obvious weak spot after Brent crude fell around 8% overnight as Washington and Tehran showed greater willingness to pursue negotiations. Woodside (WDS) -3.53% to $32.24, Whitehaven Coal (WHC) -5.05% to $7.33, New Hope (NHC) -5.40% to $5.61, Yancoal (YAL) -6.43% to $5.68 and Viva Energy (VEA) -6.57% to $2.70 were all hit hard. We hold WHC in the Growth Portfolio, and NHC in the Income Portfolio.
- Uranium also remained under pressure, with Deep Yellow (DYL) -5.44% to $0.70 and NexGen Energy (NXG) -5.40% to $11.21, while Paladin (PDN) -2.37% also declined. We hold PDN in the Growth Portfolio, & NXG in the Emerging.
- Smartgroup (SIQ) -7.97% to $11.08 was the weakest ASX 200 stock, while 4DMedical (4DX) -7.31% to $2.41, Weebit Nano (WBT) -5.51% to $2.23 and Helia Group (HLI) -5.01% to $4.74 were also among the larger losers.
- Among the heavyweights, CBA (CBA) +1.32% to $167.23, Macquarie Group (MQG) +1.17% to $254.26, Woolworths (WOW) +1.14% to $39.91 and Fortescue (FMG) +0.91% to $14.40 gained, while BHP (BHP) -0.56% to $56.42, CSL (CSL) -1.21% to $198.72 and Westpac (WBC) -0.99% to $36.82 slipped. We hold BHP & WHC in the Growth & Income Portfolios.
- Melbourne Cup: Point Of Law stormed home to win at Flemington for trainer Ciaron Maher and jockey Ethan Brown, with Maher remarkably training the first three across the line. Interestingly, Macquarie’s quant team tipped the winner again – now 3 out of the last 4 – not a bad run after a few lean years, benefitting from a tweak to their model.
- Gold: US$3,927/oz / -0.4%.
- Iron Ore: US$90.80/t / -0.5%.
- Brent crude: Fell to around US$104.19/bbl / -8.1%.
- Overseas futures were softer into our close: FTSE futures -34pts / -0.32%, S&P 500 E-mini futures -12pts / -0.16%, Dow E-mini futures -204pts / -0.39%.