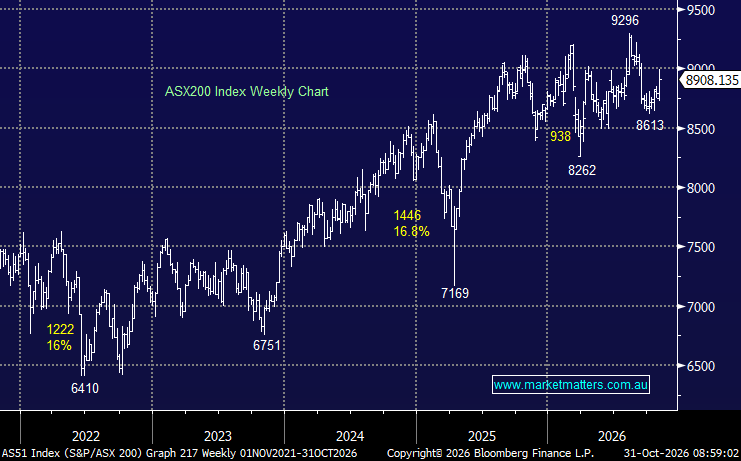
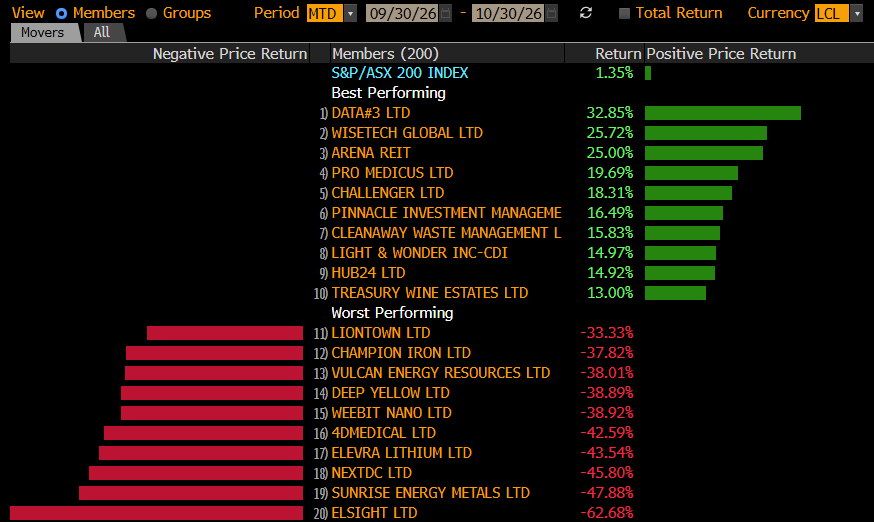
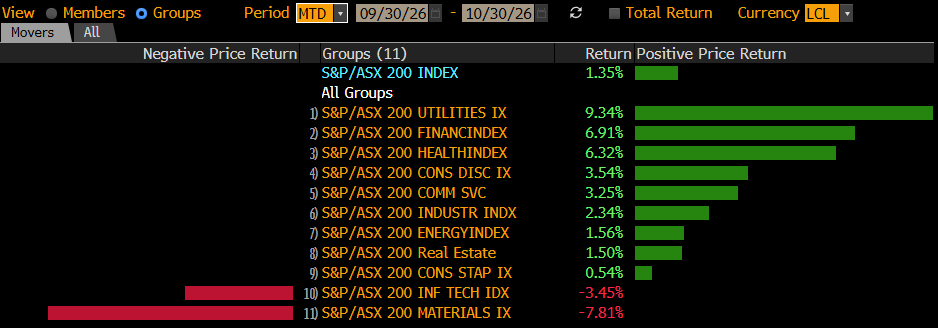
The ASX 200 finished up +1.3% last week, and +1.4% for October, an impressive performance considering the volatility on overseas markets around the AI Trade. The miners bounced well, although it’s going to be a tough start on Monday, while the banks also enjoyed a solid week, with ANZ, our preferred member of the “Big Four”, making a new all-time high. However, consumer-facing stocks remained under pressure, with the consumer staples (-5.1%) and consumer discretionary (-2.4%) sectors weighing on performance.
The best and worst-performing stocks last week were again an eclectic bunch, with rare earths and gold noticeable in the winners’ enclosure, while retail stood out on the wrong side of the ledger.
Winners: Mesoblast (ASX: MSB) +27.3%, ZIP Co (ASX: ZIP) +22.6%, IperionX (ASX: IPX) +21.1%, PDI Gold (ASX: PDI) +17.5%, Iluka Resources (ASX: ILU) +16.9%, Greatland Resources (ASX: GGP) +13.5%, Lynas Rare Earths (ASX: LYC) +13%, and Ora Banda Mining (ASX: OBM) +12.6%.
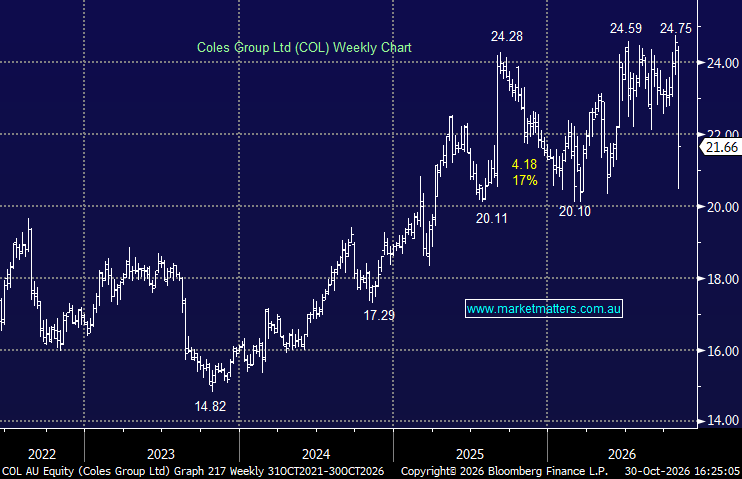
Losers: Elsight (ASX: ELS) -35.8%, 4DMedical (ASX: 4DX) -33.5%, Catalyst Metals (ASX: CYL) -17.5%, Champion Iron (ASX: CIA) -17.5%, Coles Group Ltd (ASX: COL) -11.8%, Sunrise Energy (ASX: SRL) -6.9%, Elevra Lithium (ASX: ELV) -6.2%, and Super Retail Group (ASX: SUL) -6.1%.
Weekly snapshot: The local market experienced a choppy but ultimately positive week with plenty of large intra-day moves as investors focused on different sectors day to day. Interestingly, the ASX has started to outperform technology heavy US markets which is an encouraging sign – a broadening of the rally in other words.
- The ASX 200 commenced the week on the front foot as the miners bounced strongly, with the index rallying ~1% from its early lows.
- The announcement of the Anthropic IPO lifted the miners further on Tuesday, helped by stronger-than-expected China growth data, taking the index towards 8850.
- Wednesday saw a strong start to the day reversed after the strong inflation print (CPI) resulted in the market closing marginally lower after being up ~90 points early.
- On Thursday the ASX 200 shrugged off the previous day’s hot CPI with the banks and real estate stocks rallying after the Fed left rates on hold.
- The index challenged 9000 on Friday morning before surrendering most of its early gains as weakness in global tech stocks and the local miners weighed on performance.
Next week, will see some major influences on stocks both from home and abroad:
US: The US midterm elections finally arrive on Tuesday, with fuel prices much higher than President Trump would like, and Friday’s October non-farm payrolls report will deliver another read on the likely next move by the Fed. Apple’s earnings will also be important for signs of resilience in consumer technology demand amid the recent aggressive sell-off in tech stocks.
Australia: The RBA’s Melbourne Cup-day decision on Tuesday will dominate proceedings, with markets widely expecting a 25bp hike to 4.85% following the stronger-than-expected inflation reading and hawkish commentary from policymakers. Earnings from the big banks will also be in focus, with higher rates, pressure on household spending, and ongoing weakness in global technology stocks likely to create a challenging backdrop for the ASX.
Overseas markets were heavy overnight, dominated by losses in big tech as the NASDAQ entered its 3rd correction of 2026. In Europe, the German DAX (-0.9%) and EURO STOXX 50 (-1.2%) both closed lower. However, the real action was in the US where the NASDAQ (-3.5%) weighed on the S&P 500, which retreated -1.8%.
- The SPI Futures are calling the ASX 200 to open flat on Monday despite the carnage on Wall Street and steep losses across the miners in the US.