- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
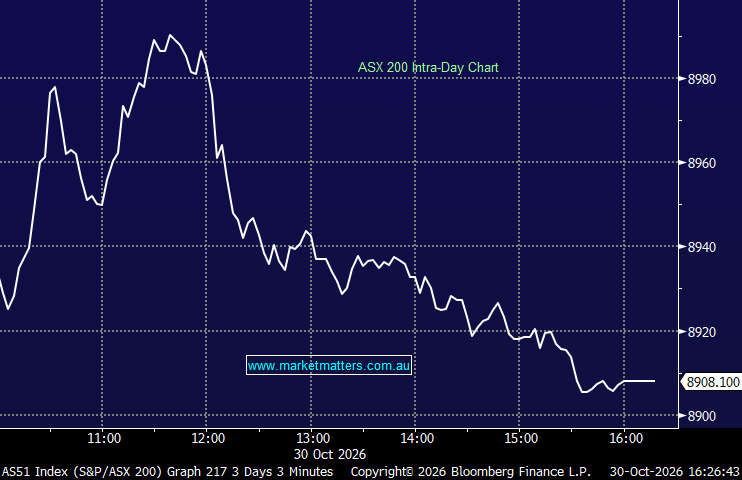
It was shaping up to be a very strong finish to October for the ASX early today, with the index up almost 1% and briefly pushing back toward 9,000 for the first time since early September. Unfortunately, the strength didn’t last. The ASX steadily gave back most of its gains through the afternoon as weakness in global technology stocks, resources and selected growth names weighed, eventually closing ~80 points below the early session highs.
The local market still had decent breadth, with eight of eleven sectors finishing higher, but the day was about rotation. Consumer Discretionary led gains – interesting given the weeks hotter CPI read and firming expectations for rate hikes, while Materials and Technology came under pressure. The narrative that we might be at the point of peak inflation and peak rates is starting to permeate through the market.
- ASX 200: +16.35pts / +0.18% to 8,908.10
- AUD/USD: 0.7033 / +0.03%
- Best sectors: Consumer Discretionary +2.73%, Industrials +1.14%, Energy +0.97%
- Worst sectors: Technology -1.34%, Consumer Staples -0.97%, Materials -0.87%
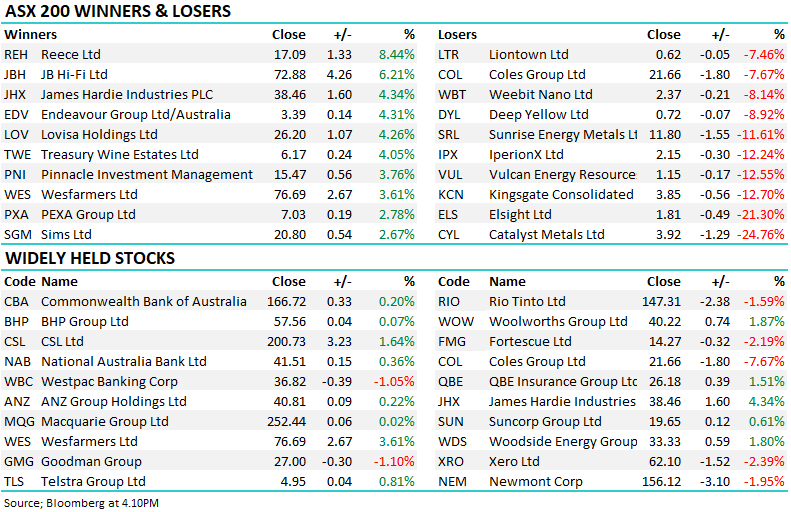
- Reece (REH) +8.44% to $17.09 topped the ASX 200 after being hit the prior session on 2 broker downgrades, while JB Hi-Fi (JBH) +6.21% to $72.88 rebounded strongly after yesterday’s weakness. UBS retained its Neutral rating on JBH but acknowledged the stock’s valuation had become more attractive after the recent pullback. We tend to agree + discretionary retail is under owned, and any sniff that rates are near a peak could see an ongoing re-rate. We own both JBH & REH in the Growth Portfolio.
- James Hardie (JHX) +4.34% to $38.46, Endeavour Group (EDV) +4.31% to $3.39, Lovisa (LOV) +4.26% to $26.20 and Treasury Wine Estates (TWE) +4.05% to $6.17 were also among the stronger performers.
- Pinnacle (PNI) +3.76% to $15.47 and Wesfarmers (WES) +3.61% to $76.69 enjoyed solid gains as money continued to rotate into some of the more beaten-up areas of the market. Wesfarmers recovering from a softer update this week, and we think this one is at or near a low.
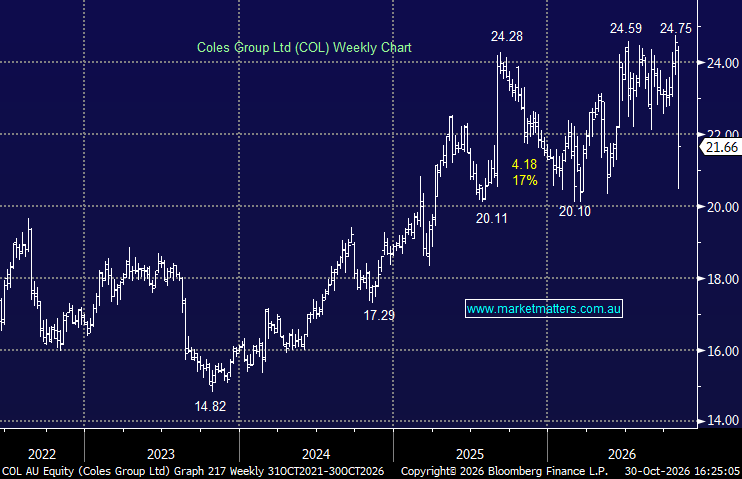
- Coles (COL) -7.67% to $21.66 was hit after a disappointing sales update triggered its worst intraday fall on record before some late buying reduced the damage. More on this below.
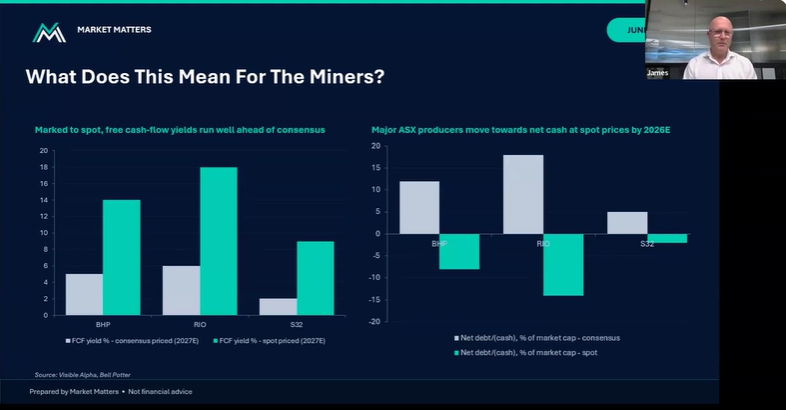
- Resources weakened into the close. Rio Tinto (RIO) -1.59% to $147.31, Fortescue (FMG) -2.19% to $14.27, Newmont (NEM) -1.95% to $156.12 and PLS (PLS) -4.00% all fell, while BHP (BHP) +0.07% to $57.56 managed to hold marginally higher. We own RIO & BHP in the Growth & Income Portfolios.
- Rio was also impacted by news that underground production at its Oyu Tolgoi copper mine in Mongolia had been halted following a rockfall that injured three people. Copper itself eased as the global technology sell-off and higher oil prices weighed.
- Lithium and uranium remained under heavy pressure. Liontown (LTR) -7.46%, Deep Yellow (DYL) -8.92%, Vulcan Energy (VUL) -12.55%, Sunrise Energy Metals (SRL) -11.61% and Lynas (LYC) -7.14% were all sharply lower.
- The speculative end of the market was particularly ugly, with Catalyst Metals (CYL) -24.76% to $3.92 and Elsight (ELS) -21.30% to $1.81 among the biggest falls.
- NEXTDC (NXT) -4.86% resumed it’s sell-off as investors continued to question the economics and funding structures surrounding the neocloud/data-centre boom. Nvidia is reportedly discussing credit guarantees for Nscale’s West Virginia data-centre project, another sign of how capital intensive the build-out has become.
- Oil moved sharply higher, with Brent December futures approaching US$117/bbl, as markets considered the possibility of renewed US military strikes against Iran post mid-terms next week
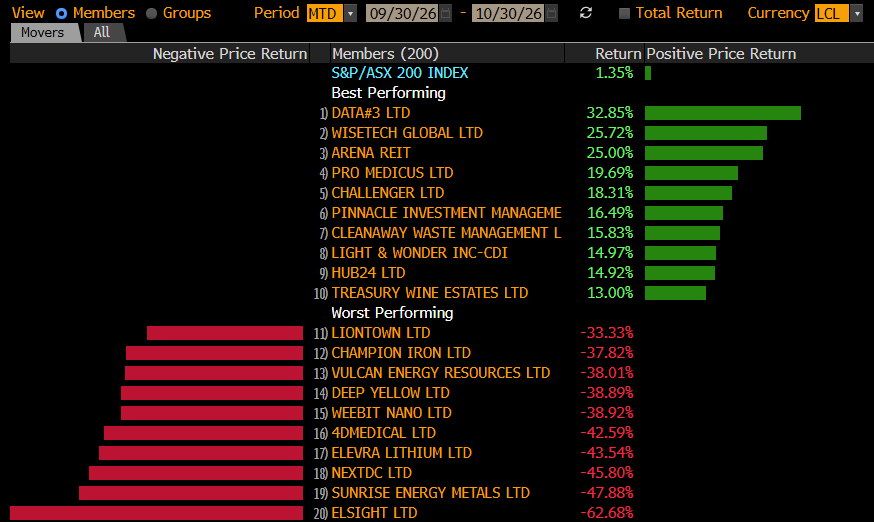
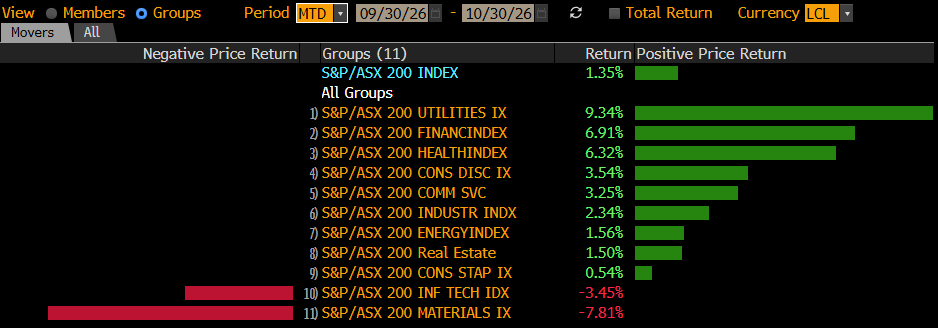
- October ultimately proved a reasonable month for Australian equities, with the ASX 200 gaining 1.35%, although again the headline index concealed some enormous moves underneath. Utilities were the standout sector, rising 9.34%, followed by Financials +6.91% and Healthcare +6.32%, while Materials fell 7.81% and Technology declined 3.45%.
- At the stock level the dispersion was even more dramatic: WiseTech gained more than 25% for the month, while a number of lithium, uranium, technology and speculative growth names fell 30–60%.
- The index has now rallied around 7.3% from its September low of 8,613, but today’s inability to hold the early push toward 9,000 is a reminder that things are still a bit sketchy.
- The good news is the recovery has broadened materially beyond resources and technology, with consumer, financial and healthcare names increasingly doing some of the heavy lifting.
- Overseas futures were mixed into the local close
- FTSE futures: +25pts / +0.23%
- S&P 500 E-mini futures: -68.25pts / -0.88%
- Dow E-mini futures: -91pts / -0.17%