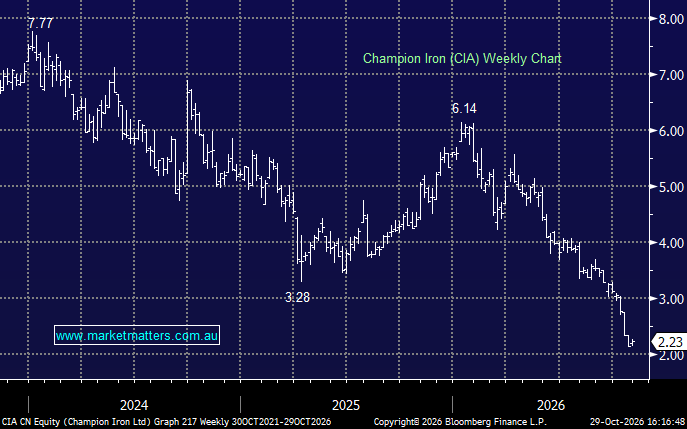
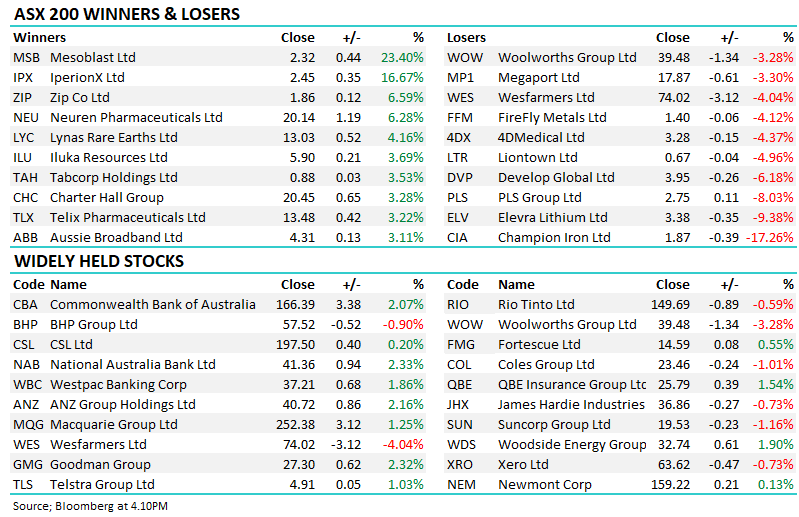
CIA –17.26%: Posted a weak second quarter result this morning, with lower iron ore prices and higher freight and fuel costs hitting earnings despite stronger sales volumes.
Key details:
- Q2 net loss of C$48.4m, versus a C$56.8m profit a year earlier.
- EBITDA fell 98% to C$3.7m, well below C$27m consensus.
- Sales volumes rose 17%, but cash costs increased 8.8% to C$82.90/dmt.
A disappointing result, highlighting the pressure on margins from weaker pricing and higher costs. The DRPF project, to upgrade iron ore concentrate into a higher-grade, lower-impurity product used to make lower-emissions steel, offers longer-term potential, but needs to scale and contribute meaningfully to earnings. For now, a recovery in margins and improved cost conditions are key to a better outlook.
MM is neutral towards CIA
Add To Hit List