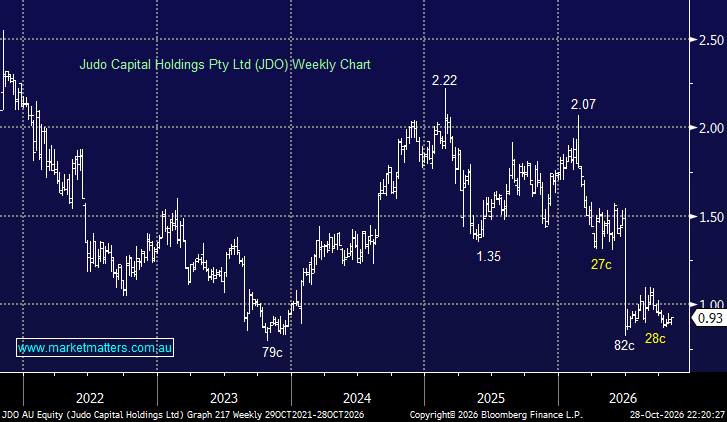
JDO was hammered in June after slashing FY26 profit guidance covered here. JDO is a major reflection of the Australian economy, being a specialist Australian bank focused on lending to small and medium-sized businesses (SMEs), as opposed to being a more traditional home loans and large corporate lender. It uses business bankers to assess each company individually, looking at the owners’ track record, cash flow, financial strength and available security.
Judo earns interest on its loans and generally seeks higher lending margins than the major banks in exchange for taking on greater credit risk and providing a more tailored service. Its performance depends on growing its loan book while managing bad debts and funding costs. These bad debts came into focus in June, and if/when interest rates rise, it’s bad news for SME’s from a macro perspective as the economy withdraws into its shell.
There’s an old saying that “you should buy the third downgrade”, and with JDO, we cannot discount such an event and would rather leave ourselves flexible as opposed to being caught if it does eventuate.
- We cannot discount another wave of concern towards JDO’s loan book, leaving us on the fence for now.
MM is neutral towards JDO around 93c
Add To Hit List