Southern Cross Electrical Engineering (SXE) rallied sharply on Tuesday following an upbeat AGM presentation, providing some welcome relief after the recent sell-off across data centre-exposed stocks. We recently suggested SXE was starting to look interesting around $3.50, following concerns around NEXTDC (NXT), neocloud funding and the broader AI infrastructure build-out. Today’s update went some way towards addressing these fears, with management reiterating strong FY27 earnings guidance and, importantly, forecasting a significant acceleration in data centre revenue despite the recent turmoil across the sector.
The standout was management’s confidence in the data centre pipeline, describing opportunities as unprecedented despite recent high-profile corporate events. SXE generated $120mn of data centre revenue in FY26 and expects this to increase to approximately $400mn in FY27, more than tripling in just 12 months. While the industry is clearly facing some funding challenges, SXE’s relationships extend across developers, tier-one builders and hyperscalers, providing more diversified exposure than the market may be giving it credit for.
Other takeaways from the AGM included:
- Earnings growth: FY27 EBITDA guidance of at least $110mn was reiterated, representing more than 40% growth on FY26’s $77mn, with further growth expected beyond FY27.
- Strong trading momentum: September delivered another record month for group revenue, surpassing the previous record set in June.
- Record order book: SXE entered FY27 with $810mn of secured work, up 18% on the prior year, providing meaningful earnings visibility.
- Acquisition upside: The recently announced acquisition of Entire Operations, expected to complete in November, adds fire protection and HVAC capabilities, with at least $10mn of EBITDA contribution expected in FY27 and pro forma EPS accretion of at least 18%.
- Increasing recurring revenue: Around 31% of FY26 revenue was recurring, with Entire expected to add more than $60mn annually, reducing reliance on major construction projects.
We see the diversification story as increasingly important. SXE is evolving from a traditional electrical contractor into a broader infrastructure services business spanning electrical, communications, fire protection, HVAC and maintenance. This allows it to capture more work from existing clients while reducing its reliance on any single sector. Importantly, management also highlighted that it doesn’t anticipate material constraints from funding, labour availability or inflation in delivering its growth ambitions.
That said, the data centre sector remains exposed to project delays and funding uncertainty, while SXE’s aggressive acquisition strategy brings integration and execution challenges. However, yesterday’s update suggests the recent share price weakness has been driven more by broader sector concerns than any deterioration in SXE’s own operating outlook.
Overall, AGM commentary was encouraging, particularly the forecast jump in data centre revenue to $400mn and confirmation of at least 40% EBITDA growth in FY27. We remain positive on SXE’s medium-term outlook, with strong earnings momentum, an expanding order book and increasing diversification supporting the investment case. We’ve had the stock on the Hitlist for a few months, and recent weakness now presents an opportunity in our view.
MM is bullish SXE ~$4
Add To Hit List
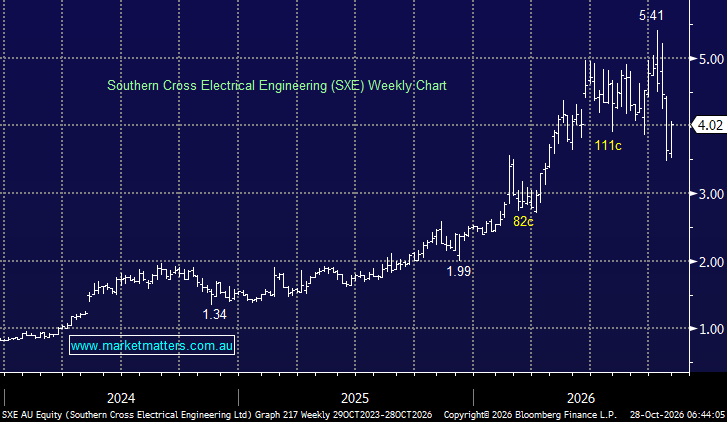
chart

Southern Cross Electrical Engineering Ltd (SXE)
chart
Southern Cross Electrical Engineering Ltd (SXE)